
Insuring a teenage driver can feel expensive, and honestly, it should. Teen drivers cause more accidents than any other age group, which is why insurance companies charge higher premiums.
The good news? You have real control over what you pay. We at Stonebrook Insurance help families find teen driver insurance quotes that fit their budget without sacrificing protection.
Why Teen Drivers Cost More to Insure
Teen drivers represent a genuine financial risk to insurance companies, and the numbers back this up. According to the National Highway Traffic Safety Administration, drivers aged 16 to 19 have crash rates three times higher than drivers aged 20 and older. This isn’t opinion-it’s documented fact based on millions of accidents annually. Insurance companies charge more because teenagers statistically file more claims, not because they’re being greedy.
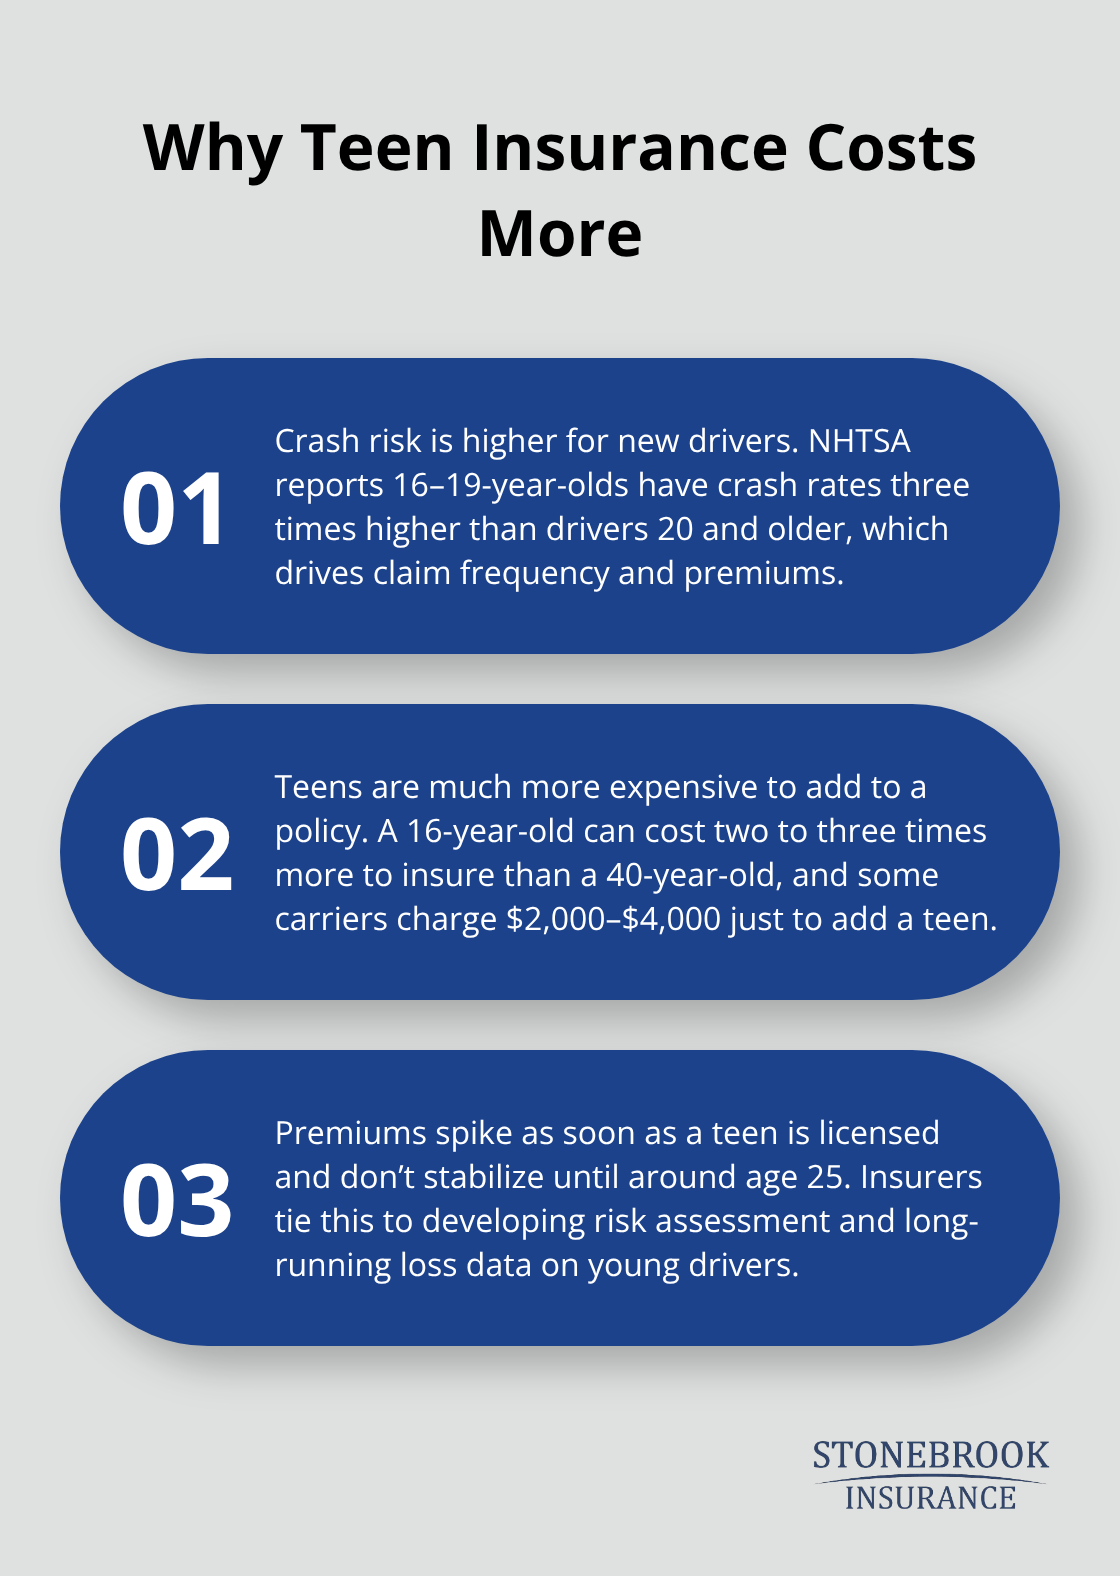
A 16-year-old driver costs roughly two to three times more to insure than a 40-year-old, depending on your state and the specific carrier. Some insurers charge $2,000 to $4,000 annually just to add a teen to a parent’s policy, while others push rates even higher. The spike happens the moment a teen gets their license and doesn’t stabilize until around age 25, when insurance companies consider the brain’s risk assessment capabilities fully developed.
Age Makes the Biggest Difference
A 16-year-old costs significantly more than a 17-year-old, who costs more than an 18-year-old. Each year matters because insurance companies track accident data by age group, and the pattern remains consistent across carriers. The jump from age 19 to 20 brings a noticeable rate decrease, but not the dramatic drop you’ll see at 25. If your teen is still several years away from driving, waiting isn’t practical, but understanding this timeline helps you anticipate costs. Some families consider adding their teen to the policy at 17 or 18 rather than 16 if circumstances allow, which can save hundreds annually.
Driving Experience and Record Impact Costs Immediately
A brand-new driver with zero accidents costs more than a teen who has driven safely for a year. One speeding ticket or minor accident can increase premiums by 20 to 50 percent depending on the carrier and severity. A DUI or reckless driving charge can double or triple rates instantly. Your teen’s first year of driving is the most expensive, and their behavior during that period directly determines whether costs increase or decrease going forward. Insurance companies use actuarial data showing that drivers who avoid incidents in their first 12 months tend to maintain better driving habits long-term, so safe first-year driving genuinely lowers future premiums.
What Happens Next With Your Quote
Understanding these cost drivers prepares you for the next critical step: shopping around with different carriers to find the best rate for your specific situation.
Where to Find the Best Teen Driver Quotes
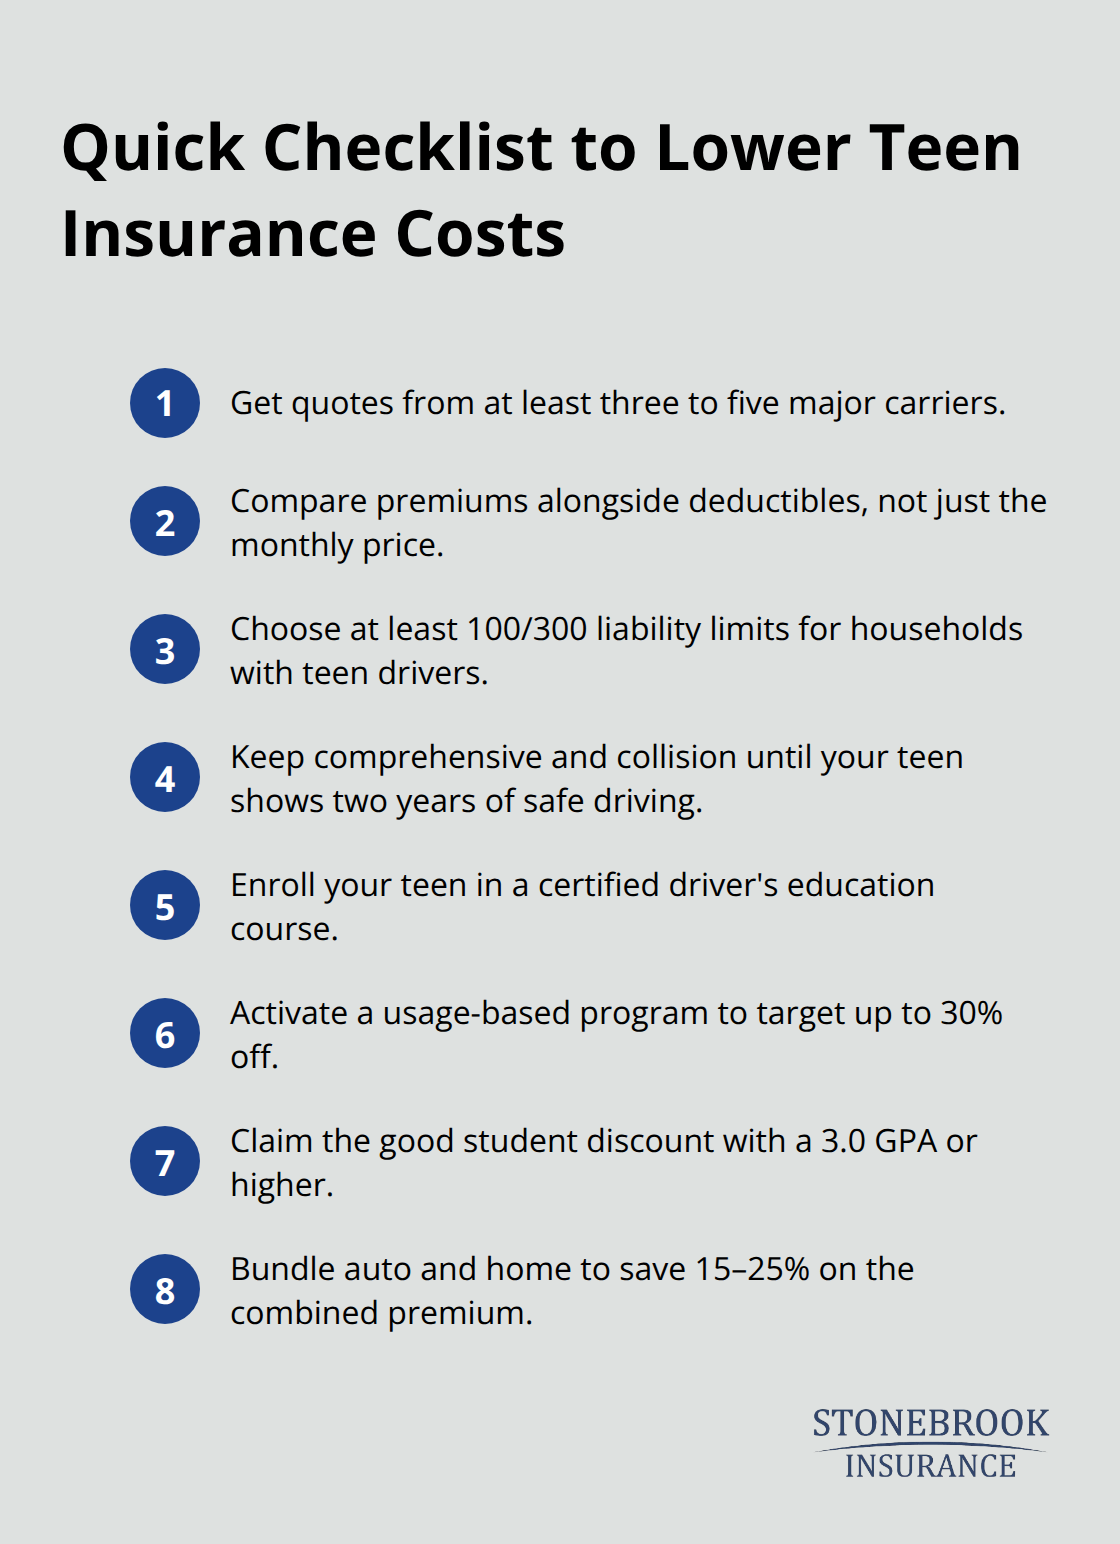
Shopping around isn’t optional if you want to save money on teen driver insurance. Most families accept the first quote they receive, which is a costly mistake. Insurance companies price teen coverage differently based on their own actuarial data and risk models, meaning the same 16-year-old could cost $2,500 at one carrier and $3,800 at another. Getting quotes from at least three to five major carriers takes roughly 30 minutes online or by phone, and the potential savings justify the effort. Some parents find differences exceeding $1,200 annually between their lowest and highest quote, which translates to $6,000 over five years. Each company weighs factors like your teen’s GPA, whether they’ll drive to school, and the vehicle type differently, creating real variation in premiums.
Deductibles and Coverage Limits Shape Your Real Costs
When comparing quotes, most people focus on the monthly premium and ignore the deductible entirely. A lower premium with a $1,000 deductible costs less upfront but exposes your family to higher out-of-pocket expenses if your teen causes an accident. A $500 deductible typically increases your monthly payment by $15 to $25, but that difference adds up to meaningful protection. For teen drivers specifically, try not to go higher than a $750 deductible because teen accident rates mean you’re more likely to use it.
Coverage limits matter equally. State minimum liability coverage ranges from $15,000 to $30,000 per person depending on your state, but this is dangerously low. An accident causing serious injury could result in a lawsuit exceeding $100,000, which you’d pay personally if your coverage maxes out. Most insurance professionals recommend $100,000 per person and $300,000 per accident at minimum for households with teen drivers. Comprehensive and collision coverage protects your vehicle itself, and while optional if your car is paid off, they’re worth maintaining until your teen demonstrates consistent safe driving for at least two years.
Teen-Specific Discounts Cut Costs Significantly
Insurance companies offer discounts specifically designed for teen drivers that many parents never claim. The most valuable is the good student discount, which can save you up to 25% on your auto insurance when your teen maintains a 3.0 GPA or higher. This discount appears on quotes from nearly every major carrier. Driver’s education courses also qualify for discounts ranging from 5 to 15 percent, and some carriers extend this benefit for three years after completion. Progressive and State Farm both advertise substantial discounts for completing certified driver training programs.
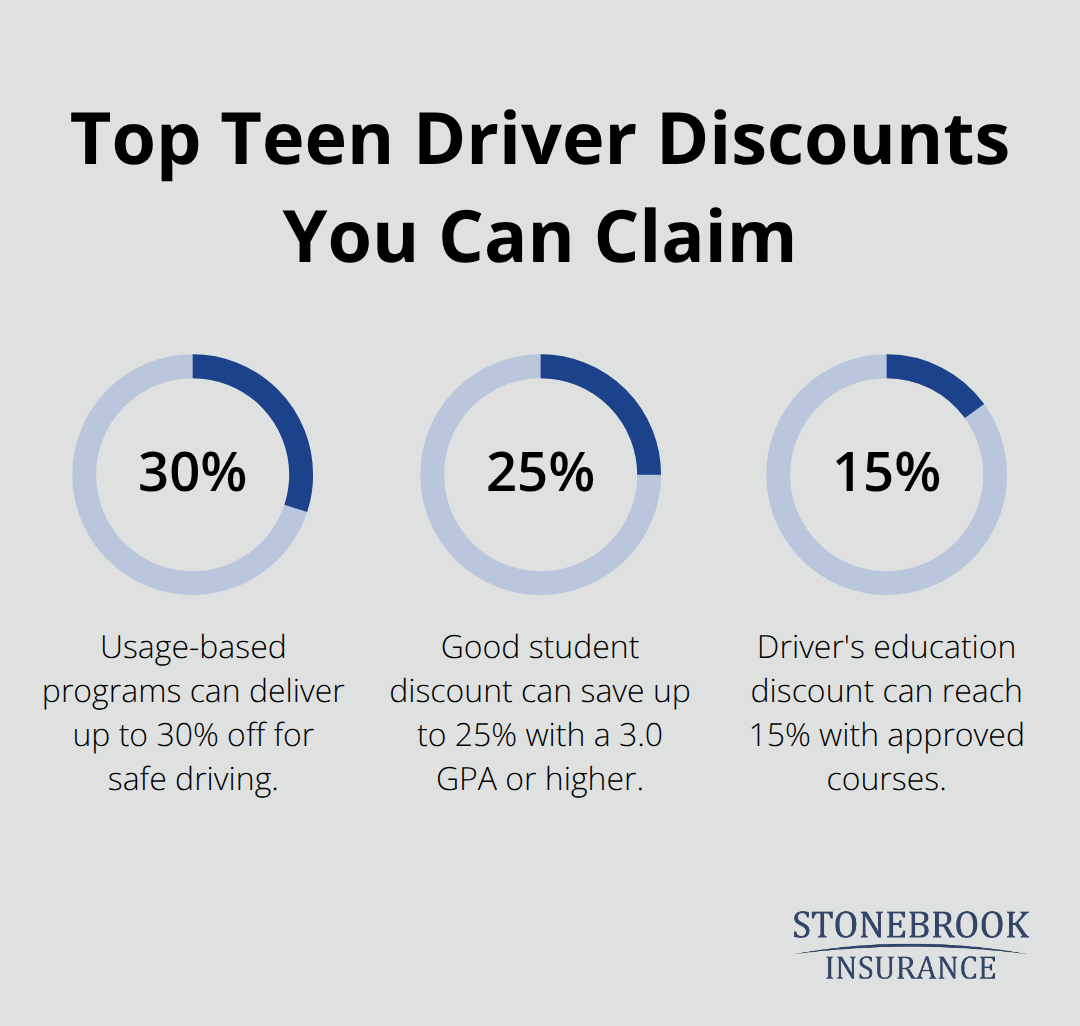
Usage-based insurance programs, sometimes called telematics programs, offer the biggest potential savings for safe teen drivers. These programs monitor your teen’s actual driving habits through a smartphone app or device, and safe drivers can earn discounts up to 30 percent. Milewise from Progressive and SafetyNet from State Farm let parents see real-time driving data while teens earn rewards for avoiding hard braking and speeding. For families bundling auto and home insurance, bundle discounts typically save 15 to 25 percent on the combined premium. You must ask about each discount specifically when requesting quotes, as they don’t always appear automatically.
What Comes Next in Your Quote Comparison
Once you’ve gathered quotes with the right deductibles, coverage limits, and discounts applied, the next step involves evaluating which carrier actually offers the best value for your teen’s specific situation.
How to Actually Lower Your Teen’s Insurance Costs
Good Grades Reduce Your Premium Directly
Good grades genuinely reduce what you pay for teen insurance, and this isn’t a marketing gimmick. The good student discount applies when your teen maintains good grades, and most major carriers offer this discount automatically on quotes. You’ll save up to 25 percent depending on the carrier, which translates to $300 to $600 annually for many families. Allstate, State Farm, and Progressive all honor this discount, making it one of the easiest wins available. The logic works: students who maintain decent grades tend to demonstrate responsibility in other areas, including driving. Your teen’s first report card after getting their license matters more than you might think because that’s when you lock in this discount with their carrier. If your teen’s grades drop, many insurers allow you to reinstate the discount once grades improve, but you’ll need to provide proof.
Safe Driving Records Protect Your Wallet
Safe driving records work similarly, but here’s the uncomfortable truth: a single accident or ticket during your teen’s first year can eliminate any savings you’ve gained. One speeding ticket costs roughly $150 to $300 in fines, but your insurance premium increase dwarfs that amount. A minor accident typically raises premiums by 20 to 50 percent for three years, meaning a $1,500 annual policy becomes $1,800 to $2,250. A DUI or reckless driving conviction can increase rates by 100 to 300 percent, making insurance cost $3,000 to $4,500 annually. The math here is brutal: avoiding one accident saves your family thousands over your teen’s driving lifetime.
Usage-Based Programs Reward Safe Behavior
Usage-based insurance programs flip this dynamic by rewarding safe behavior directly. Progressive’s Milewise and State Farm’s SafetyNet monitor actual driving through smartphone apps, and safe drivers receive discounts up to 30 percent. These programs track hard braking, speeding, and nighttime driving, giving your teen real-time feedback on their habits. Families using these programs report that teens drive more cautiously when they know they’re monitored, which reduces accidents and keeps premiums low. The discount kicks in immediately after 30 to 60 days of safe driving data, so your teen sees the financial benefit of good behavior quickly.
Bundle Policies for Maximum Savings
Bundling your auto and home insurance with the same carrier saves 15 to 25 percent on your combined premium, which adds up fast when you’re insuring multiple vehicles. If you currently have your home insurance with one company and auto with another, consolidating saves money immediately. Most families don’t realize their current insurer offers better rates on bundled policies than what they’re paying separately. Shopping multiple carriers at once (rather than accepting your first quote) ensures you capture every discount available for your specific situation.
Final Thoughts
Finding affordable teen driver insurance quotes requires action across three fronts. Shop quotes from at least three to five major carriers because rate differences regularly exceed $1,200 annually for identical coverage. Apply every available discount your teen qualifies for, particularly the good student discount and usage-based insurance programs, which together can reduce premiums by 40 to 50 percent.
Your teen’s first year of driving determines their insurance trajectory for years to come. Safe driving records, good grades, and consistent behavior lower costs immediately and compound savings over time. One accident or ticket during this critical period can eliminate years of discounts, so the investment in monitoring and encouraging safe habits pays real dividends.
We at Stonebrook Insurance shop multiple major carriers to find teen driver insurance quotes tailored to your family’s needs and budget. Our team identifies discounts you’d miss on your own and secures competitively priced coverage backed by local service across three Texas locations. Contact us at stonebrookagency.com to get started with quotes that actually save you money.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.