
Standard homeowners insurance falls short when you own multiple properties, valuable collections, or host frequent events on your estate. HNW homeowners insurance in Texas is built differently-with higher limits, specialized coverage, and the flexibility that affluent lifestyles demand.
At Stonebrook Insurance, we’ve spent over 30 years helping high-net-worth clients across Texas find protection that actually matches their assets and risk profile.
How HNW Homeowners Insurance Differs from Standard Coverage
Coverage Limits That Match Your Assets
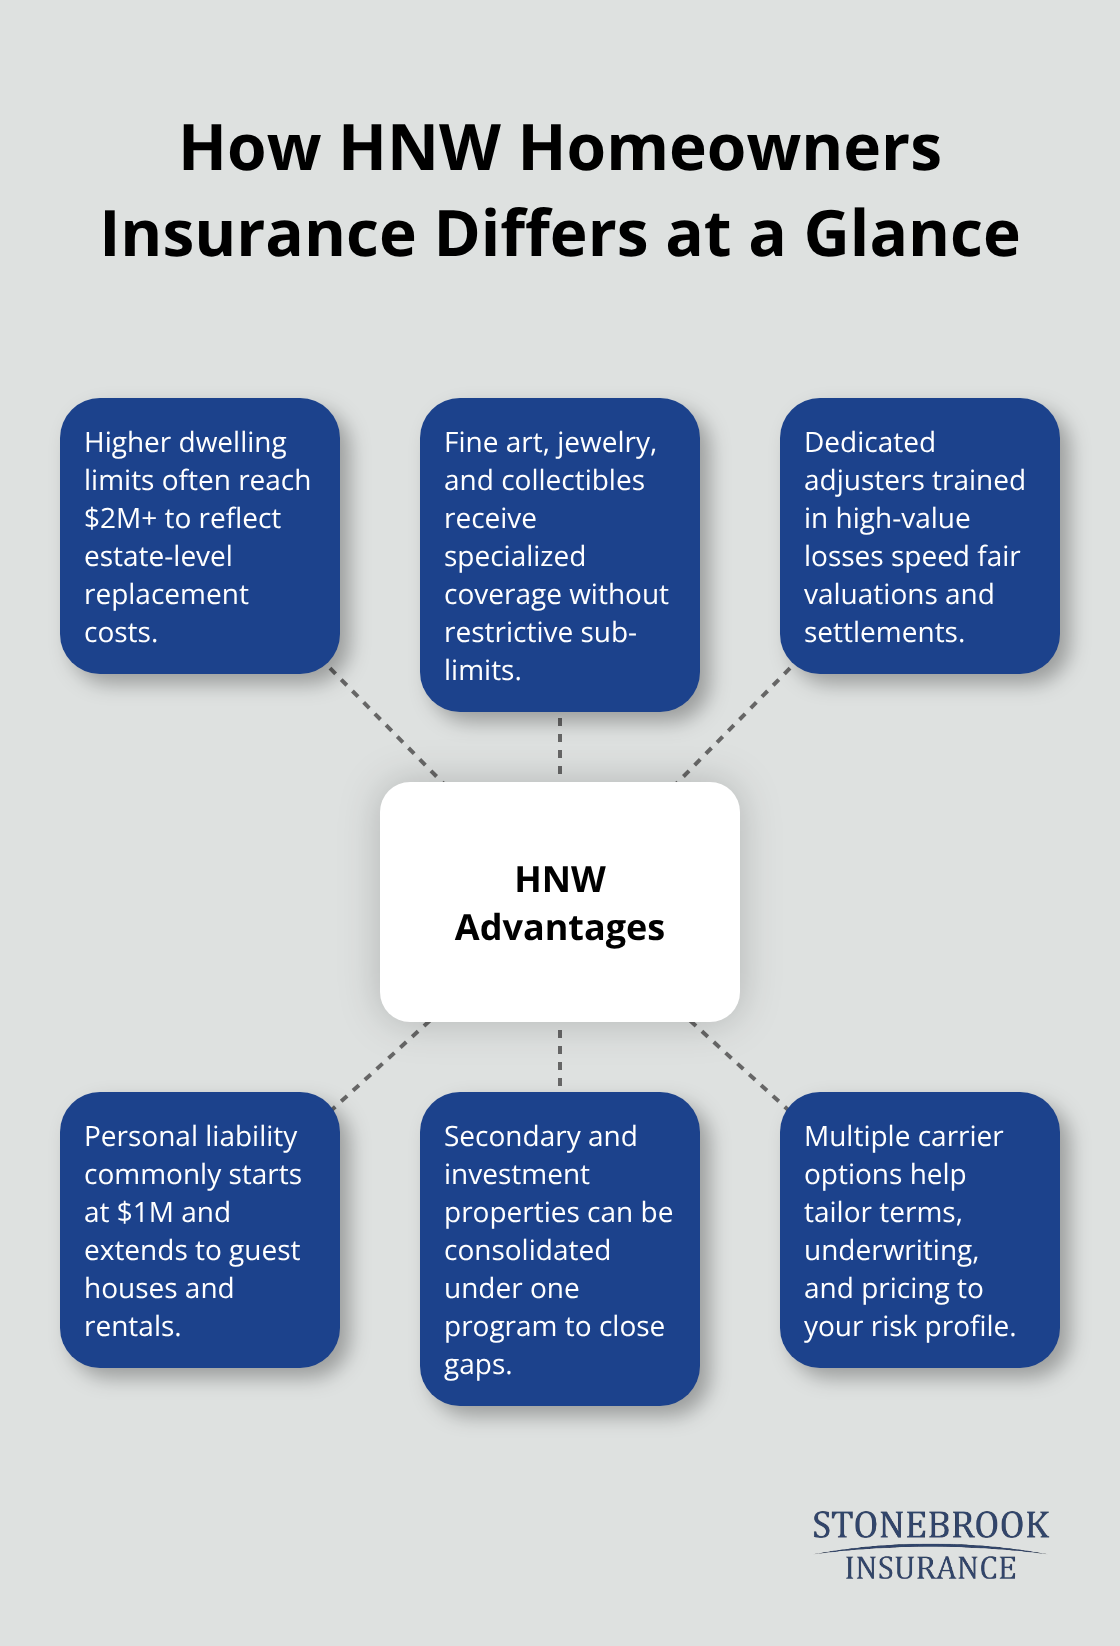
Standard homeowners insurance typically caps dwelling coverage at $300,000 to $500,000 and personal property limits around $100,000. For affluent Texas homeowners, these numbers fall far short. HNW policies start where standard coverage ends, with dwelling limits that can reach $2 million or higher and personal property coverage exceeding $500,000. The gap between what you own and what standard policies protect creates serious financial exposure.
Specialized Protection for Luxury Assets
Standard policies treat your $400,000 art collection, rare wine collection, or custom jewelry the same way they treat basic household goods. They apply blanket limits and depreciation rules that leave you significantly underinsured on high-value items. HNW policies recognize that luxury assets require specialized coverage for fine art, antiques, and collectibles without the restrictive sub-limits that devastate claims on these items. A standard policy’s approach to valuation and replacement simply doesn’t work for assets that appreciate or require expert appraisal.
Claims Handling Built for High-Value Losses
When you file a claim on a $50,000 piece of jewelry under a standard policy, an adjuster managing hundreds of claims simultaneously handles your case. HNW claims get assigned to specialists trained in valuing luxury items, understanding complex loss scenarios, and expediting settlements for high-value claims. This difference in attention and expertise directly affects how quickly you recover and how fairly your loss gets valued.
Liability Coverage for Your Lifestyle
Texas homeowners with estates, guest houses, or rental properties face liability risks that standard homeowners policies inadequately address. Hosting a charity gala where a guest is injured, or maintaining rental income properties, creates exposure that standard coverage excludes or severely restricts. HNW coverage includes liability limits of $1 million or higher and extends to secondary properties and income-generating activities. This protection reflects the actual risks that come with affluent property ownership and entertaining.
The specialized nature of HNW insurance means your coverage options expand significantly beyond what standard policies offer-which brings us to the specific protections available to affluent Texas homeowners.
What Coverage Actually Protects Your Wealth
High-Value Possessions Need Blanket Protection
Affluent Texas homeowners own multiple properties, maintain collections worth hundreds of thousands of dollars, and host events that expose them to liability risks standard insurers won’t touch. The gap between what you own and what basic coverage protects creates real financial vulnerability. HNW policies address this by offering blanket coverage for high-value possessions that doesn’t apply arbitrary sub-limits to your most valuable items. Instead of capping jewelry at $2,500 or artwork at $5,000 like standard policies do, specialized HNW coverage protects individual pieces worth $100,000 or more without depreciation penalties. A $250,000 jewelry collection stays fully protected, not reduced to a fraction of its actual value when you file a claim.
Secondary Properties Require Integrated Coverage
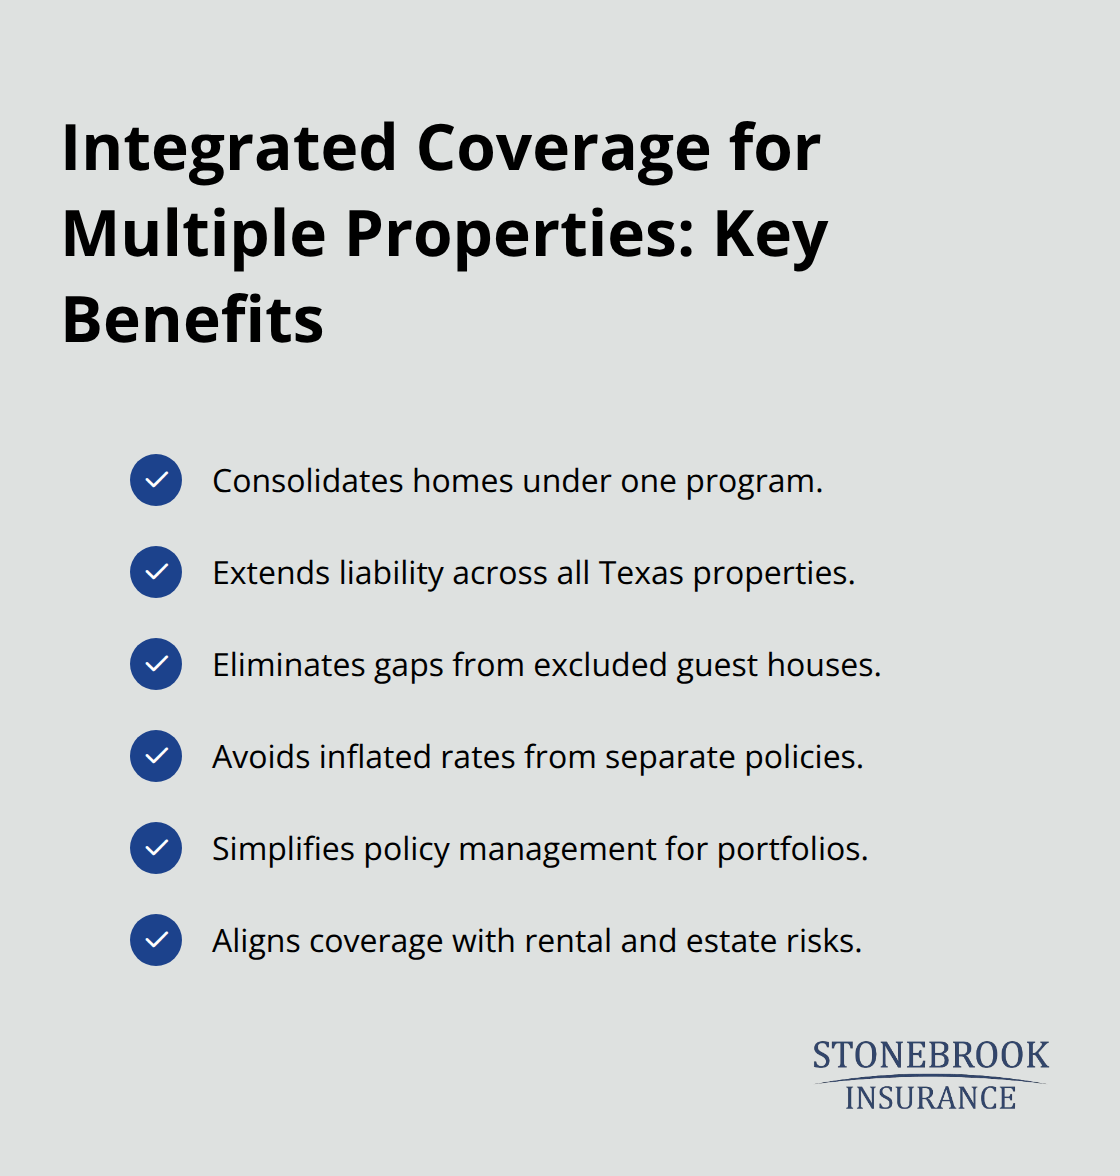
Secondary properties and investment homes present coverage challenges that standard homeowners policies simply refuse to handle. A rental property or guest house on your estate typically gets excluded from your primary home policy, leaving you underinsured or forcing you to buy separate policies at inflated rates. HNW policies integrate protection for multiple properties under one program, with liability coverage extending across all your Texas properties. This consolidated approach eliminates coverage gaps that plague affluent homeowners managing diverse real estate portfolios.
Liability Limits That Match Your Entertaining
Liability limits jump to $1 million or higher in HNW policies, which matters significantly when you host events on your estate or maintain rental income properties. Texas homeowners who entertain frequently face substantial exposure, particularly if a guest suffers an injury during a charity event or private gathering. Standard policies cap liability at $300,000 to $500,000, leaving you personally liable for amounts exceeding that threshold. Specialized HNW coverage recognizes that your entertaining and business activities create risks that demand higher limits and broader protection than residential policies provide.
The specific assets you own and the activities you pursue on your property determine which coverage options make the most sense for your situation. Understanding what protection actually exists for art, jewelry, and collectibles helps you identify gaps in your current coverage.
Why Multiple Carriers Matter for Your HNW Coverage
Insurance Companies Price Identical Coverage Differently
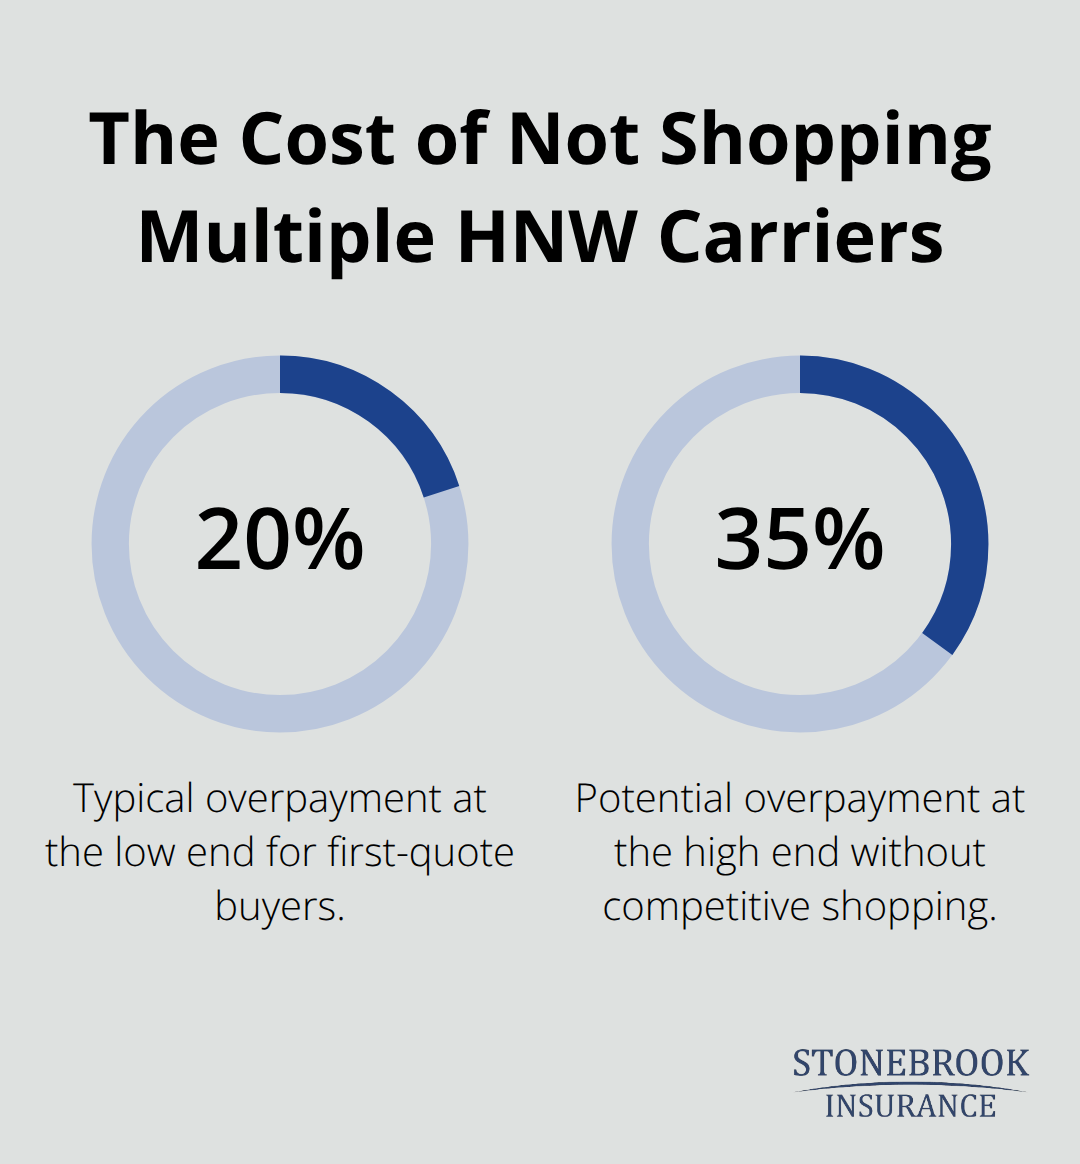
Finding the right HNW homeowners insurance in Texas requires more than accepting the first carrier that quotes a high limit. Insurance companies price identical coverage differently based on their appetite for specific risk profiles, their claims experience in your area, and their underwriting guidelines. When you work with an agency that shops multiple major carriers, the difference between a competitive quote and an overpriced one often reaches $3,000 to $5,000 annually on HNW policies. A single carrier might decline to cover your rental guest house or charge a penalty for your art collection, while another carrier actively competes for that exact risk. Affluent homeowners who accept the first quote they receive typically overpay by 20% to 35% compared to what competitive shopping reveals.
Regional Differences Demand Local Knowledge
Your $2 million estate in McKinney faces different exposure than one in rural Comanche, and your insurance should reflect those differences rather than applying a one-size-fits-all approach. Insurance carriers adjust their rates and coverage terms based on local risk factors-weather patterns, theft rates, water availability for fire suppression, and neighborhood characteristics all influence what you pay and what protection you receive. An agency with locations across different Texas regions understands how these variables affect your specific property and can match your situation to carriers equipped to handle it efficiently.
Complex Asset Portfolios Require Specialized Underwriting
When you own five properties with varying characteristics, maintain a valuable art collection, and host regular events, standard underwriting processes create delays and coverage gaps. Most carriers apply generic questionnaires and automated systems that don’t account for the nuances of protecting complex asset portfolios. An agency that works regularly with high-net-worth clients develops relationships with specialized coverage for high-net-worth homeowners in Texas and understand the specific risks you face. This personalized approach matters most when your assets fall outside conventional homeowner profiles-it directly translates to better coverage and fair pricing for your circumstances.
Carrier Relationships Accelerate Your Coverage Process
The complexity of your situation-multiple properties, high-value possessions, frequent entertaining-makes carrier selection critical rather than incidental. An agency with established relationships at carriers that actively compete for HNW business can expedite underwriting, clarify coverage options, and negotiate terms that work for your portfolio. Without those relationships, you navigate carrier websites and generic quotes that don’t address your specific needs.
Final Thoughts
HNW homeowners insurance in Texas protects what standard policies ignore-higher coverage limits, specialized protection for luxury assets, and claims handling built for complex portfolios address the real gaps that affluent homeowners face. When you own multiple properties, maintain valuable collections, or host frequent events on your estate, the difference between adequate coverage and underinsurance reaches hundreds of thousands of dollars. The carriers you choose matter as much as the coverage you select, since insurance companies price identical protection differently based on their appetite for specific risks and underwriting guidelines.
Shopping multiple major carriers typically reveals savings of $3,000 to $5,000 annually on HNW policies and identifies carriers equipped to handle your particular asset portfolio without restrictions or penalties. Regional factors affect your specific property and risk profile in ways that generic quotes miss entirely. An agency with local knowledge and established carrier relationships finds competitive rates and specialized coverage that actually matches your assets and lifestyle.
Contact Stonebrook Insurance to discuss your specific situation with someone who understands high-net-worth protection. We’ll review your current coverage, identify gaps, and show you what competitive shopping reveals about your options. Protecting your wealth requires more than accepting the first quote you receive-it requires an agency that knows your market and has the carrier relationships to deliver tailored solutions.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.