
Your custom home represents a significant investment, but standard homeowners policies often fall short in protecting it. High-end materials, specialized systems, and unique architectural features require coverage that goes beyond what typical policies offer.
At Stonebrook Insurance, we understand that custom home insurance in Texas demands a different approach. We’ll show you how to close the gaps in your coverage and safeguard your property properly.
Why Custom Homes Cost More to Replace
Custom homes in Texas command higher replacement costs than standard properties, and this difference becomes painfully obvious when you need to rebuild. A standard home might cost $150 to $200 per square foot to reconstruct, but custom builds with imported materials, handcrafted details, and specialized systems often exceed $300 to $500 per square foot. The gap widens further when your home includes features like Italian marble countertops, custom cabinetry built on-site, or architectural elements that mass production cannot replicate. Standard homeowners policies calculate coverage based on generic replacement costs, which means they systematically undervalue what your home actually costs to rebuild.
The Problem with Standard Policy Limits
A typical Texas homeowners policy caps dwelling coverage at a predetermined amount that bears little relationship to your actual property. If your custom home is worth $1.2 million but your policy limits max out at $750,000, you face catastrophic financial loss. When a fire, hail storm, or wind event damages your custom features, the insurer won’t cover the specialized labor and materials needed to restore them to their original condition. This gap between what you own and what your policy covers represents the core problem that custom home insurance must solve.
Specialty Systems and Construction Methods
Your custom home likely contains systems and construction methods that standard policies simply don’t account for. Smart home automation, radiant floor heating, geothermal systems, and custom structural solutions require specialized knowledge to repair or replace. If your home features a metal roof, stone veneer, or advanced insulation techniques, a standard adjuster may not understand the true cost of restoration. Texas-specific risks like hail damage and high winds create additional complexity for custom homes, since replacement materials may need to match existing finishes that are no longer in production. Standard policies exclude or severely limit coverage for these specialized elements, leaving you to pay out of pocket for restoration that preserves your home’s integrity and value.
Why Replacement Cost Matters More Than Market Value
Market value and replacement cost are two entirely different numbers for custom homes. Your home might sell for $1 million on the open market, but rebuilding it from scratch could cost $1.5 million or more. Insurance companies often base coverage on market value rather than true replacement cost, which creates a dangerous shortfall.
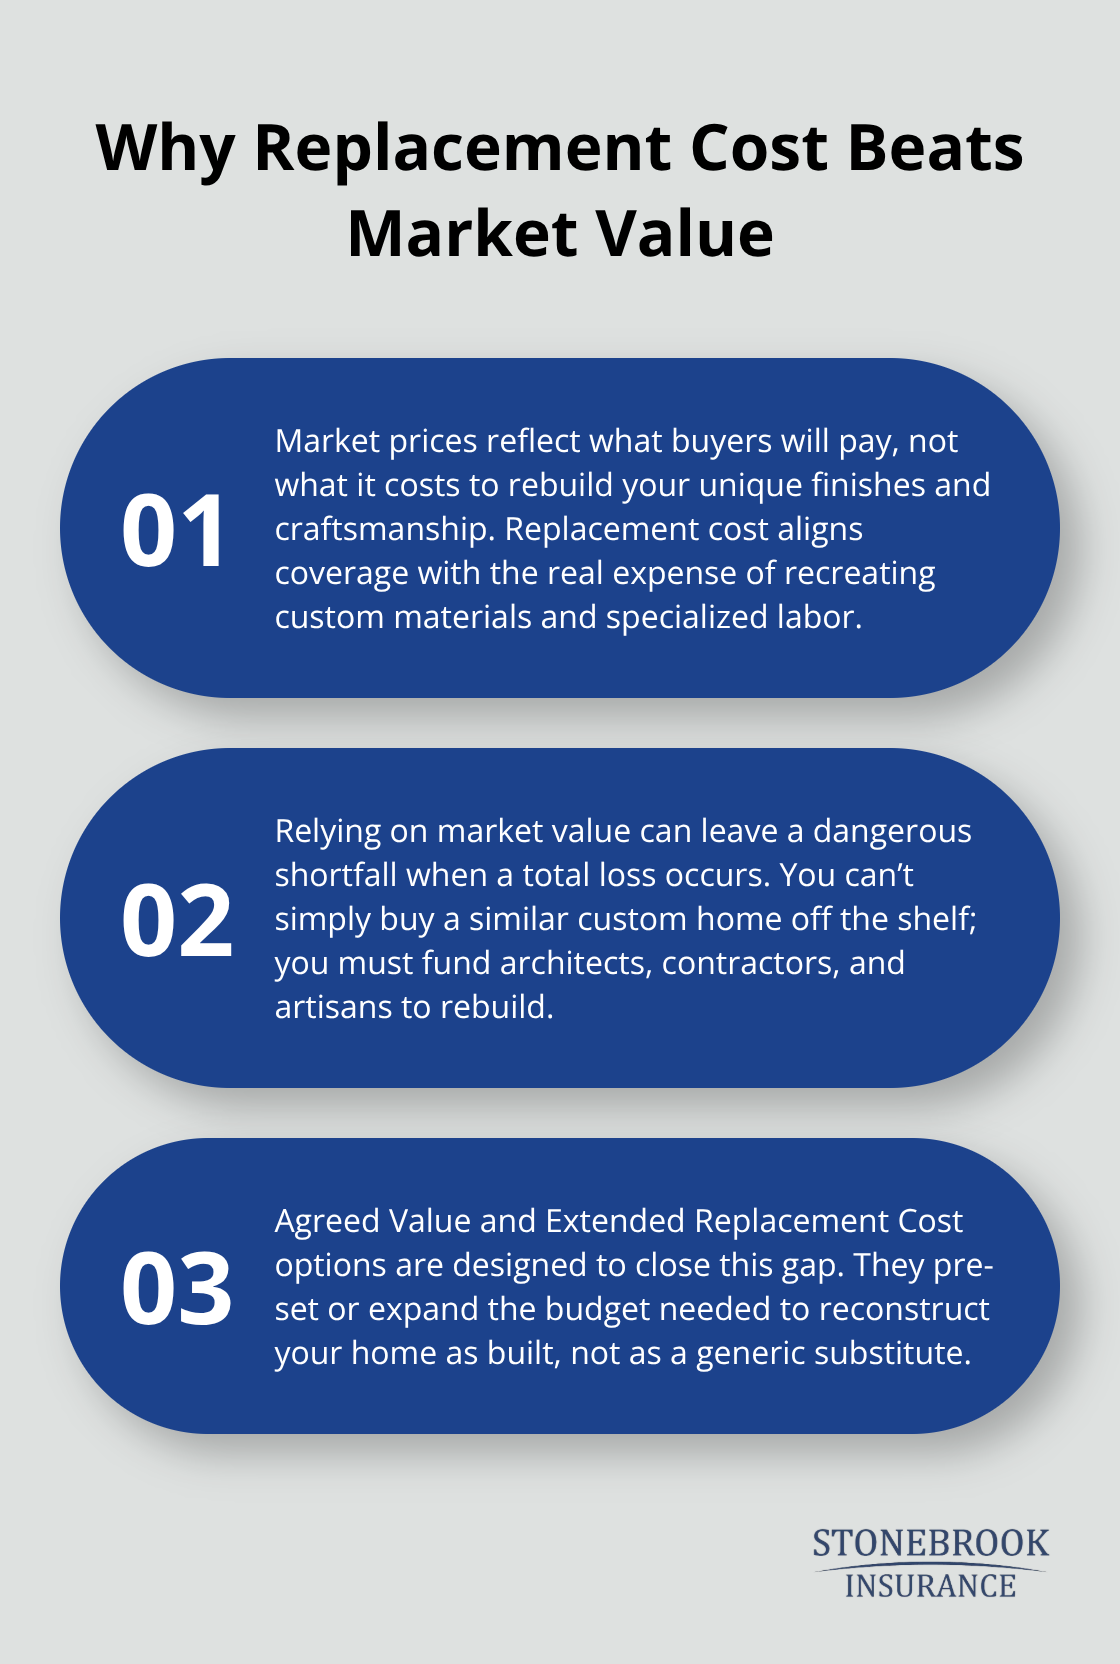
When you need to rebuild after a total loss, you cannot simply buy another custom home at market price-you must pay contractors, architects, and specialized craftspeople to recreate what you lost. Custom home insurance addresses this reality by offering Agreed Value or Extended Replacement Cost options that align your coverage with actual rebuilding expenses, not what your property would fetch in a sale.
Where Standard Policies Fall Short for Custom Homes
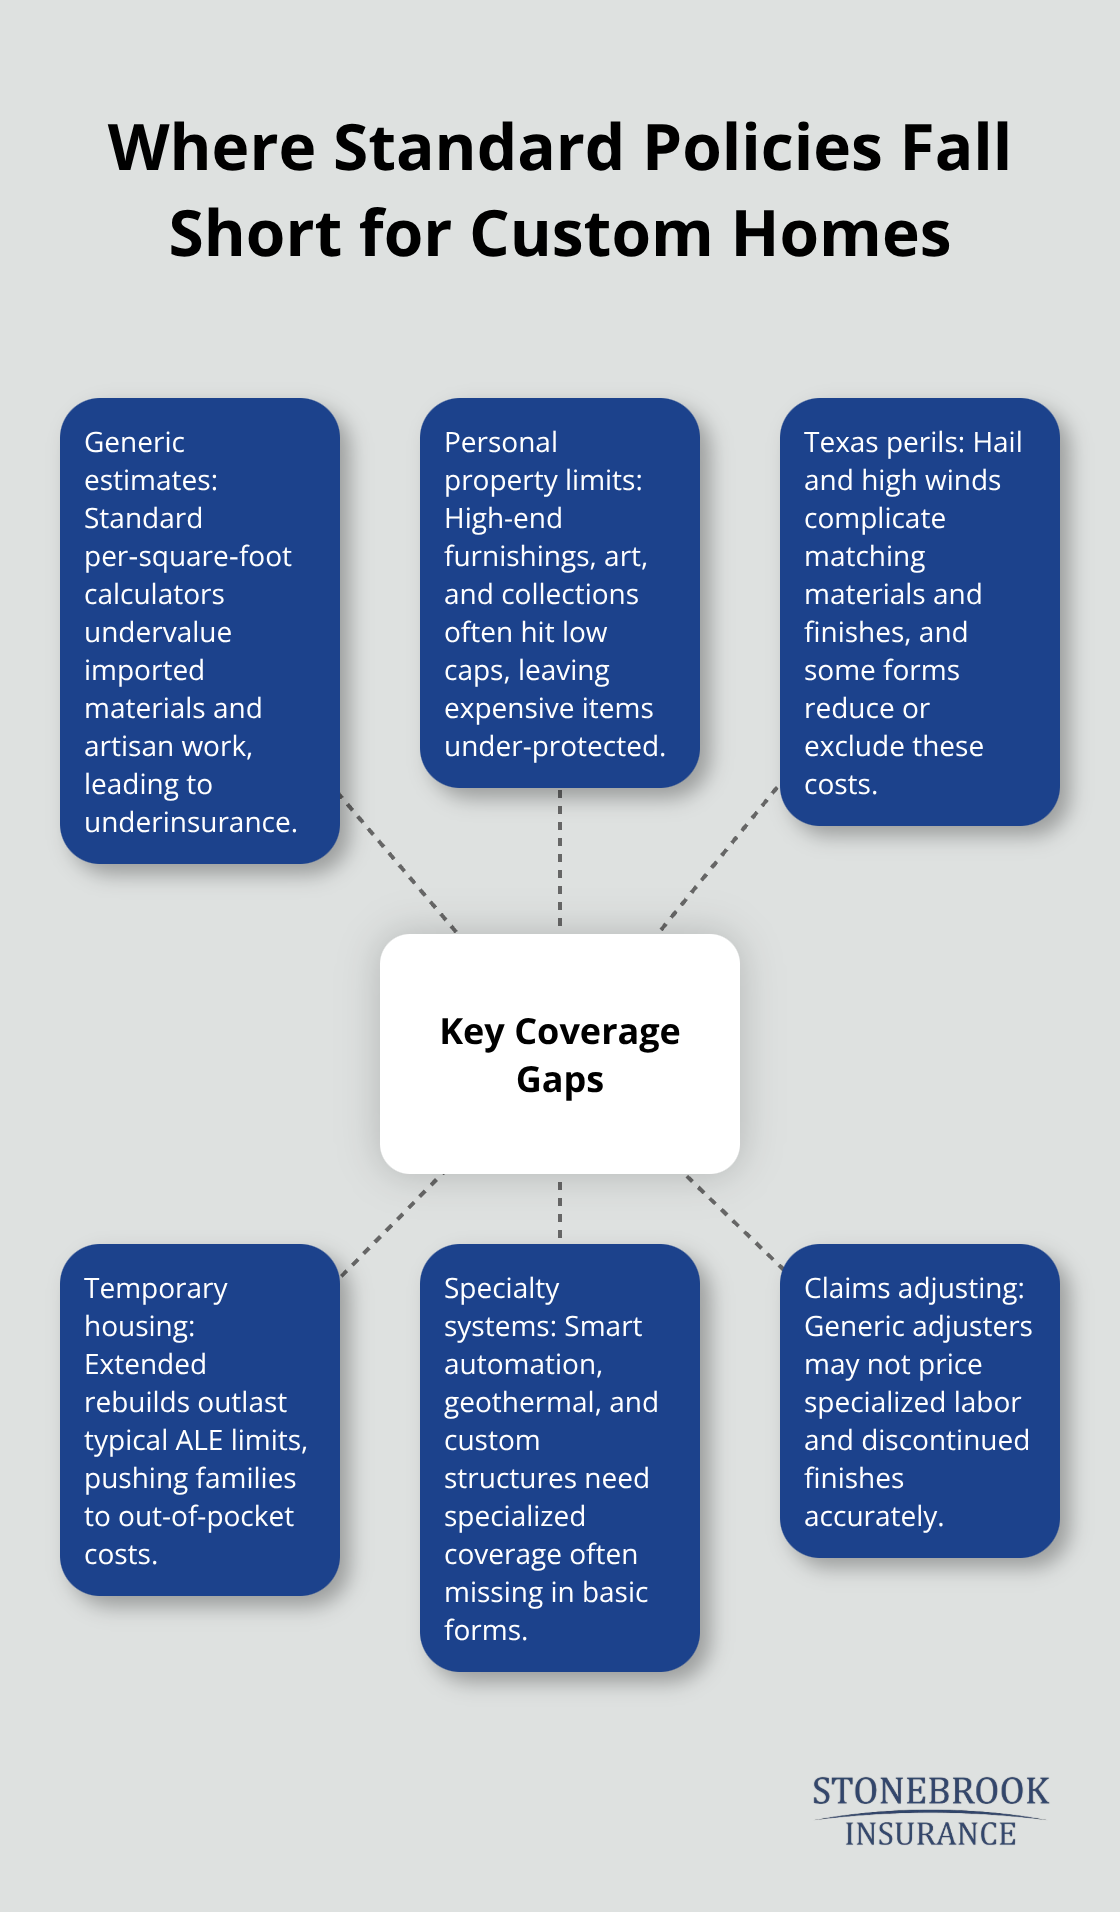
Generic Cost Estimates Miss Your Home’s True Value
Standard homeowners policies operate on a one-size-fits-all model that treats your custom home like any tract house in a suburban development. The insurer establishes coverage limits based on square footage and generic per-square-foot replacement costs, typically ranging from $150 to $200 per square foot across Texas. For a custom home with imported stone, handcrafted millwork, or specialized finishes, this approach guarantees underinsurance. When you file a claim for damage to Italian marble countertops or custom cabinetry built by local artisans, the adjuster applies standard replacement rates that don’t account for the actual cost of matching materials or recreating specialized work. You end up covering the difference yourself, sometimes thousands of dollars per room.
Personal Property and Specialty Features Receive Inadequate Limits
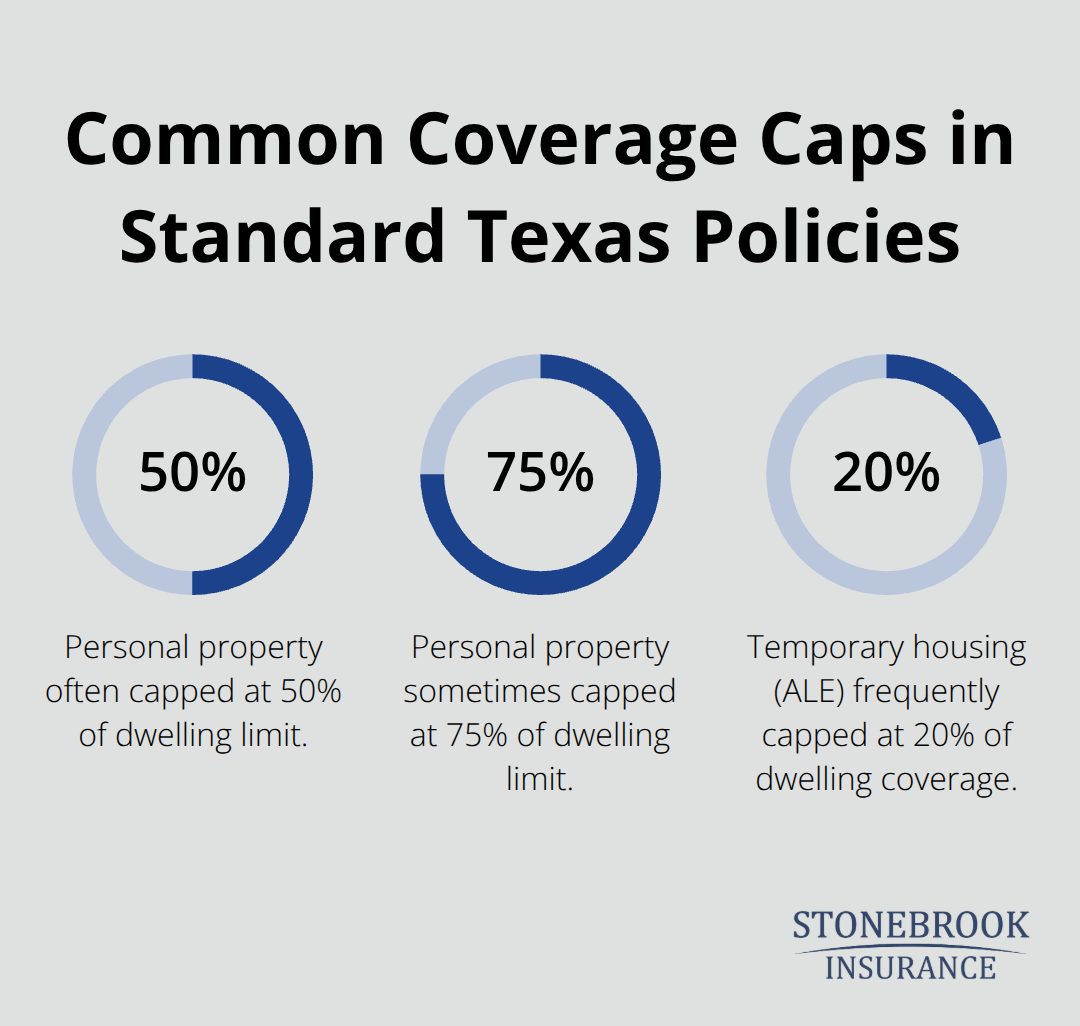
The real damage emerges when you examine what standard policies explicitly exclude or severely limit. Most standard Texas homeowners policies cap personal property coverage at 50 to 75 percent of your dwelling limit, which means high-end furnishings, artwork, and collectibles receive inadequate protection. If your home contains a wine cellar, home theater, or fitness suite, these additions typically fall outside standard coverage or receive minimal limits. Smart home systems, geothermal heating, radiant floor systems, and custom structural elements designed for your specific property don’t fit the adjuster’s playbook.
Texas Perils Create Coverage Gaps for Custom Features
Texas-specific perils compound the problem significantly. Hail damage to a metal roof or architectural shingles that match custom exterior finishes may be covered at reduced rates or excluded entirely depending on your policy form. Wind damage to custom outdoor structures like pergolas, pavilions, or specialty landscaping rarely receives adequate coverage under standard policies. The Texas Department of Insurance reports that homeowners in high-risk areas face coverage gaps precisely where they need protection most.
Temporary Housing Limits Leave You Stranded During Reconstruction
Standard policies also fail to account for the extended rebuilding timeline that custom homes require. If your home needs specialized contractors, imported materials, or architectural oversight to restore properly, temporary living expenses under a standard policy may cap out at 20 percent of dwelling coverage, leaving you in a hotel or rental property longer than your policy covers. This forces you to either live in substandard temporary housing or drain your savings while waiting for reconstruction.
How Tailored Coverage Closes These Gaps
Custom home insurance addresses these gaps directly by offering replacement cost coverage that matches your home’s actual rebuilding expenses, not market value or generic cost estimates. This specialized approach protects what makes your home exceptional-and that protection becomes essential when you understand exactly what standard policies leave exposed. The next section shows you how custom home insurance actually works to safeguard your investment.
How Custom Home Insurance Protects Your Investment
Custom home insurance fundamentally changes how your coverage aligns with your property’s actual value. Instead of applying generic per-square-foot estimates, insurers specializing in custom homes conduct detailed property assessments that account for your specific materials, systems, and construction methods. This means coverage reflects what it truly costs to rebuild your Italian marble countertops, handcrafted cabinetry, and custom architectural details rather than what mass-produced alternatives would cost.
Agreed Value and Extended Replacement Cost Coverage
Agreed Value coverage eliminates the guesswork entirely. You and your insurer establish a fixed rebuild cost before a loss occurs, and that amount stays guaranteed regardless of market fluctuations. Extended Replacement Cost options go further, covering up to 125 or 150 percent of your stated limit if reconstruction expenses exceed projections due to material scarcity or specialized labor requirements. For Texas custom homes facing hail, wind, and wildfire risks, this approach prevents the catastrophic shortfall that catches standard policyholders unprepared.
Specialty Systems and High-Value Personal Property
Your home’s specialty systems like geothermal heating, radiant floor installations, and smart home automation receive explicit coverage limits tailored to their actual replacement costs rather than being squeezed into generic personal property limits. High-value personal property such as fine art, jewelry, and collectibles can be scheduled individually with documented appraisals, ensuring these items receive full replacement value rather than the 50 to 75 percent limits standard policies impose.
Extended Temporary Housing Coverage
Custom home insurance addresses the extended reconstruction timeline that standard policies ignore completely. If your home requires specialized contractors, imported materials sourced from overseas, or architectural coordination to match existing finishes, temporary housing coverage extends far beyond the 20 percent cap standard policies provide. Some carriers offer additional living expense coverage that accounts for the months-long rebuilding process custom homes typically require, protecting you from draining savings while waiting for craftspeople and materials to restore your property.
Comprehensive Protection for Complex Exposures
Water backup protection, equipment breakdown coverage, and liability limits customized to your specific exposures round out the protection. Carriers experienced in custom home coverage understand that your property requires different protection than a standard Texas residence. When you work with an independent agency that shops multiple carriers, you gain access to underwriters who recognize the true complexity of custom homes and can match you with policies that actually fit what you own.
Final Thoughts
Custom homes demand insurance that recognizes their complexity and value. Standard policies systematically underinsure what you own, leaving dangerous gaps when hail, wind, or fire strikes. Custom home insurance in Texas addresses this reality by aligning coverage with actual replacement costs, protecting specialty systems, and accounting for the extended reconstruction timelines that custom properties require.
We at Stonebrook Insurance understand that custom homes represent far more than financial investments-they reflect your vision, taste, and the craftsmanship of specialized builders and artisans. Our team shops multiple major carriers to find underwriters who actually understand custom construction, specialty systems, and high-value personal property. We conduct detailed assessments of your materials, finishes, and unique features to build coverage that matches what you own.
Contact Stonebrook Insurance to schedule a consultation about your custom home’s specific coverage needs. We’ll review your property, identify gaps in your current protection, and present options from carriers that specialize in homes like yours. Your custom home deserves insurance as distinctive as the property itself.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.