
Your luxury home deserves protection that matches its value. Standard homeowners policies leave significant gaps when it comes to high-end properties, leaving you exposed to financial risk.
At Stonebrook Insurance, we specialize in high net worth home insurance designed specifically for elite properties. We’ll show you how to close those coverage gaps and protect what matters most.
Why Standard Homeowners Policies Fail Luxury Homes
The Mismatch Between Standard Coverage and High-Value Properties
Standard homeowners insurance was designed for average properties with average risk profiles. A typical policy from a major carrier covers the dwelling structure up to its stated limit, personal belongings up to 50–70% of the dwelling limit, liability protection usually capped at $300,000, and basic guest medical payments. This one-size-fits-all approach crumbles when applied to high-value homes. A $5 million estate with custom architectural features, museum-quality art collections, and rare wine cellars cannot fit into underwriting formulas built for $400,000 houses. The National Flood Insurance Program handles flood coverage federally, but standard policies exclude earthquakes entirely-a significant gap for properties in seismically active regions where premiums vary dramatically based on construction type and location. Jewelry, fine art, and collectibles face strict sublimits; a diamond bracelet worth $50,000 might receive only $2,500 in coverage under a standard homeowners policy. Liability exposure for affluent homeowners hosting events, employing staff, or maintaining pools and guest houses far exceeds the $300,000 baseline. When your home includes a home theater, wine vault, or indoor pool, standard policies treat these as ordinary rooms rather than specialized risk centers requiring enhanced protection.
Specialized Assets Require Specialized Coverage
High-net-worth homes demand agreed-value coverage rather than replacement-cost formulas that underestimate true values in luxury markets. A custom marble staircase or imported Italian tile cannot be replaced at commodity prices; insurers need detailed appraisals and documentation to set accurate limits. Seasonal occupancy patterns in resort markets like Vail create gaps when a property sits vacant for months, triggering coverage restrictions standard policies impose on unoccupied dwellings. The complexity intensifies with multi-location assets-artwork rotating between a primary residence and a secondary property needs transit and temporary-location coverage most standard policies simply do not offer.
Exposures That Generic Underwriting Overlooks
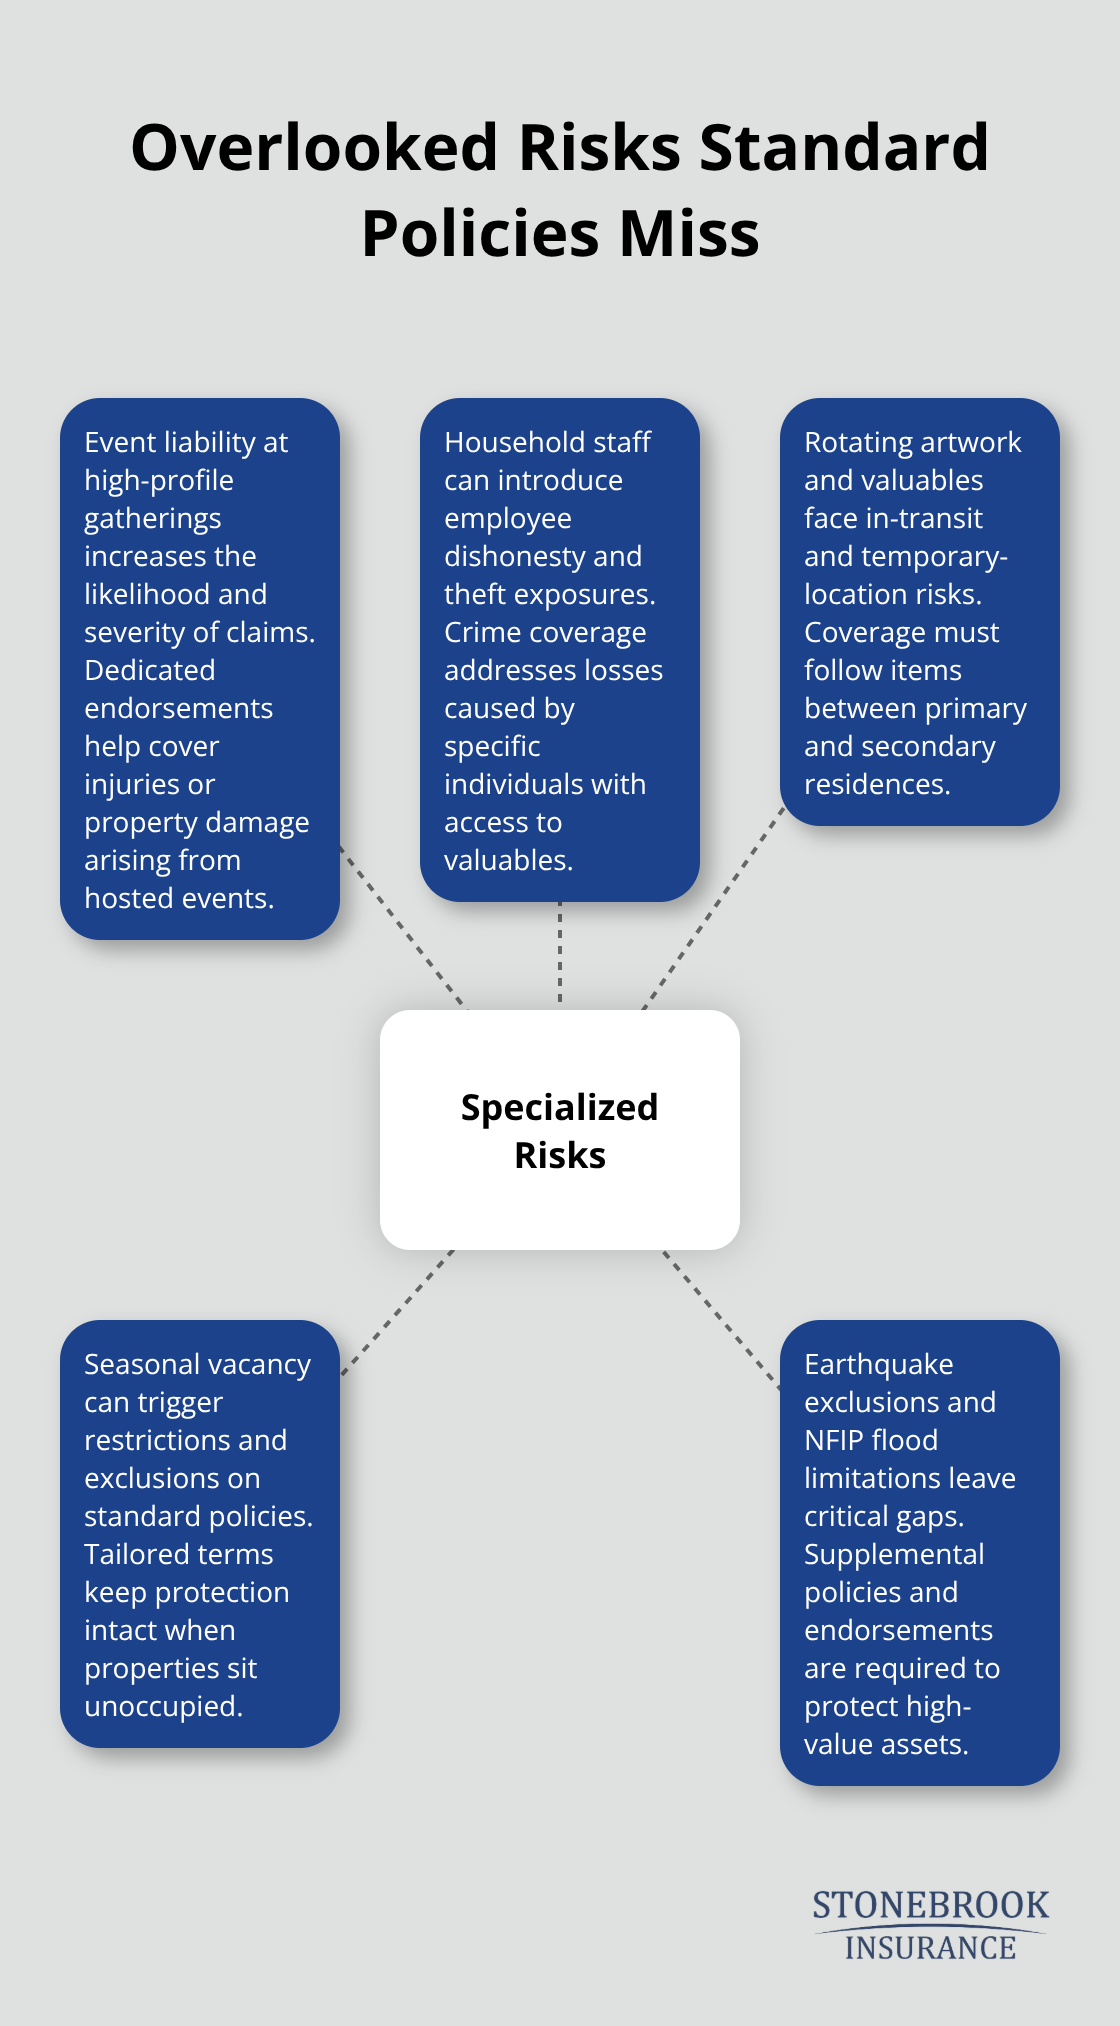
Elite homeowners face exposure that mass-market underwriting ignores: event liability when hosting high-profile gatherings, employee dishonesty coverage if household staff manage valuables, and crime insurance for theft by specific individuals. These specialized endorsements require underwriters who understand luxury asset composition and can quantify risk accordingly. Working with carriers experienced in high-net-worth underwriting versus mass-market insurers creates a measurable difference in claim outcomes, coverage responsiveness, and premium competitiveness for properties exceeding $2 million in value.
This is where specialized brokers step in to bridge the gap between what standard policies offer and what elite properties actually need.
Building Coverage That Matches Your Actual Wealth
Agreed-Value Coverage: The Foundation of Protection
Agreed-value coverage forms the foundation of proper high-net-worth protection, and this distinction matters more than most homeowners realize. Standard policies use replacement cost, which sounds straightforward until you face a claim on a custom marble staircase or imported Italian tile work. Replacement cost in standard underwriting formulas assumes commodity pricing-the insurer calculates what it costs to rebuild using standard materials and labor rates. Your actual replacement involves sourcing matching marble from the same quarry, potentially flying in specialized artisans, and managing extended timelines. Agreed-value coverage eliminates co-insurance penalties and guarantees full coverage up to policy limits. You and the insurer establish the replacement cost upfront through professional appraisals, and that amount is what you receive if a covered loss occurs. For a $3 million home with custom finishes, this difference can mean $200,000 to $400,000 in claim recovery. The process requires detailed property inspections and documentation, but this upfront work protects you when it matters most.
Umbrella Liability: Extending Your Protection Layer
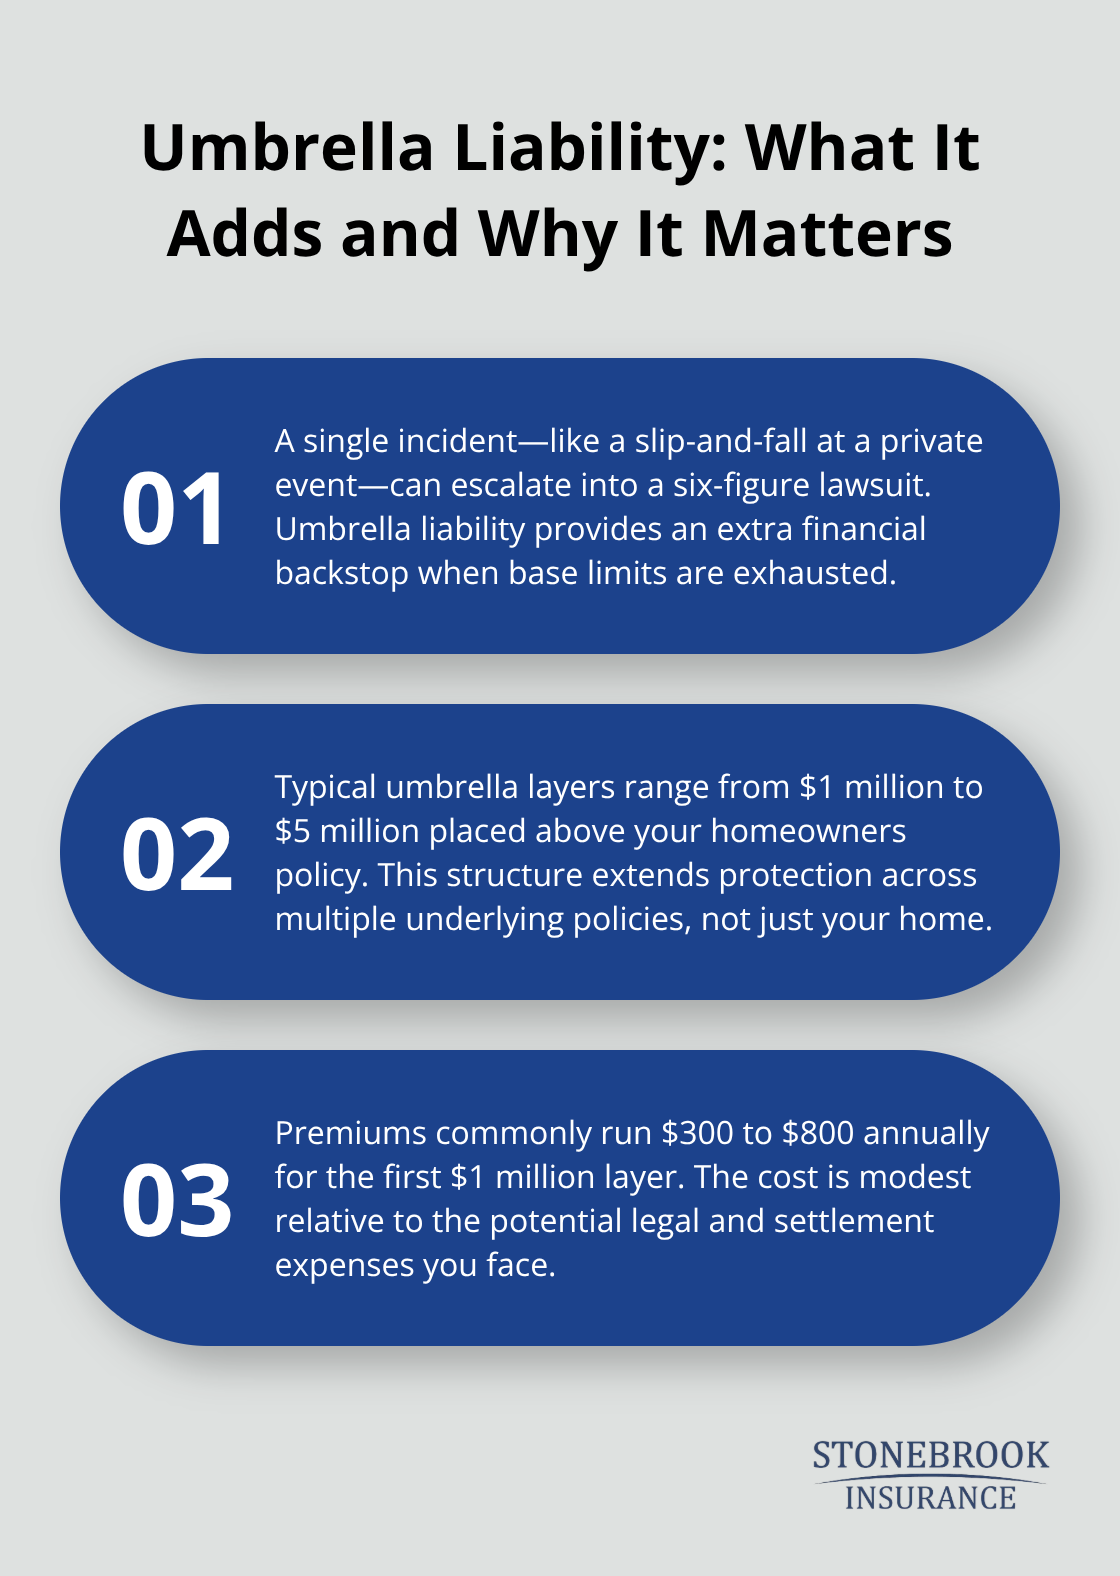
Liability exposure for affluent homeowners extends far beyond the $300,000 standard limit. If you host charitable galas, maintain a guest house for visiting family, employ household staff, or operate a home office with client meetings, your exposure multiplies. A single slip-and-fall incident at a private event can trigger a six-figure lawsuit. Umbrella coverage adds an additional $1 million to $5 million in liability protection above your homeowners policy, and premiums typically range from $300 to $800 annually for that $1 million layer. This protection costs far less than the financial risk it covers.
Scheduled Personal Property: Removing Sublimit Restrictions
Art, jewelry, wine collections, and other high-value items face strict sublimits under standard policies-often capping coverage at $2,500 for jewelry or $5,000 for fine art regardless of actual value. Scheduled personal property endorsements remove these caps entirely. You list each item with its appraised value, and coverage applies to that full amount. A diamond necklace worth $75,000 receives $75,000 in coverage, not the standard $2,500. Photography and fine art require appraisals from certified professionals, not auction estimates or insurance company valuations. These appraisals establish agreed values and support claim settlements.
Specialized Coverage for Collections and Multiple Properties
The National Flood Insurance Program excludes artwork and collectibles entirely, so properties in flood-prone areas require separate inland marine coverage for these items. For wine collections, specialized wine-vault coverage accounts for temperature control failures and theft, with premiums based on collection value and security measures. A $500,000 wine collection in a properly secured, climate-controlled vault costs roughly $1,500 to $2,500 annually to insure-a fraction of the replacement cost. For items rotating between a primary residence and a secondary property, transit coverage protects during movement and temporary storage. This matters significantly for affluent families with multiple homes or those lending pieces to exhibitions. Each location and movement scenario introduces distinct exposures that standard policies simply cannot address, which is why carriers specializing in high-net-worth underwriting build these protections into their standard offerings rather than treating them as expensive add-ons.
How We Serve High Net Worth Clients
Understanding Your Property Beyond Its Price Tag
The difference between a mass-market insurance agent and a specialist becomes obvious the moment you face a complex claim on a $3 million property. Mass-market agents follow underwriting scripts designed for standard homes. They input your property value, run it through a pricing algorithm, and quote you a policy that leaves gaps. Specialists approach high-net-worth underwriting differently. We at Stonebrook Insurance start by understanding your property’s actual composition, not just its purchase price. A detailed risk assessment identifies which assets fall outside standard coverage limits, which endorsements you actually need, and where competitors leave you exposed.
This process takes time. A comprehensive review involves property inspections and appraisals for high-value items, documentation of custom features, and conversations about how you use your home. When you host events regularly, maintain a guest house, or employ household staff, these operational details shape your coverage structure. Most brokers skip this work because it requires expertise and effort. Specialists complete it because claim outcomes depend on it.
Identifying Coverage Gaps That Matter
We review your current coverage line-by-line to identify sublimit restrictions on jewelry or art, confirm flood and earthquake exclusions, and map out the exact protection gaps that matter for your situation. This assessment becomes the foundation for building a tailored policy that actually matches your wealth and lifestyle. A $5 million estate with custom architectural features, museum-quality art collections, and rare wine cellars cannot fit into underwriting formulas built for $400,000 houses. Standard policies treat a home theater, wine vault, or indoor pool as ordinary rooms rather than specialized risk centers requiring enhanced protection.
Access to Multiple Carriers and Competitive Pricing
Access to multiple premium carriers separates competitive brokers from discount-focused agents who lock you into one company’s pricing. Stonebrook shops your risk across carriers that specialize in high-net-worth underwriting, not just the three largest national companies. Carriers experienced in elite properties understand agreed-value coverage, handle complex endorsements efficiently, and price competitively for properties exceeding $2 million. You receive quotes from multiple underwriters with expertise in your specific situation-whether that involves art collections, wine vaults, or seasonal occupancy patterns.
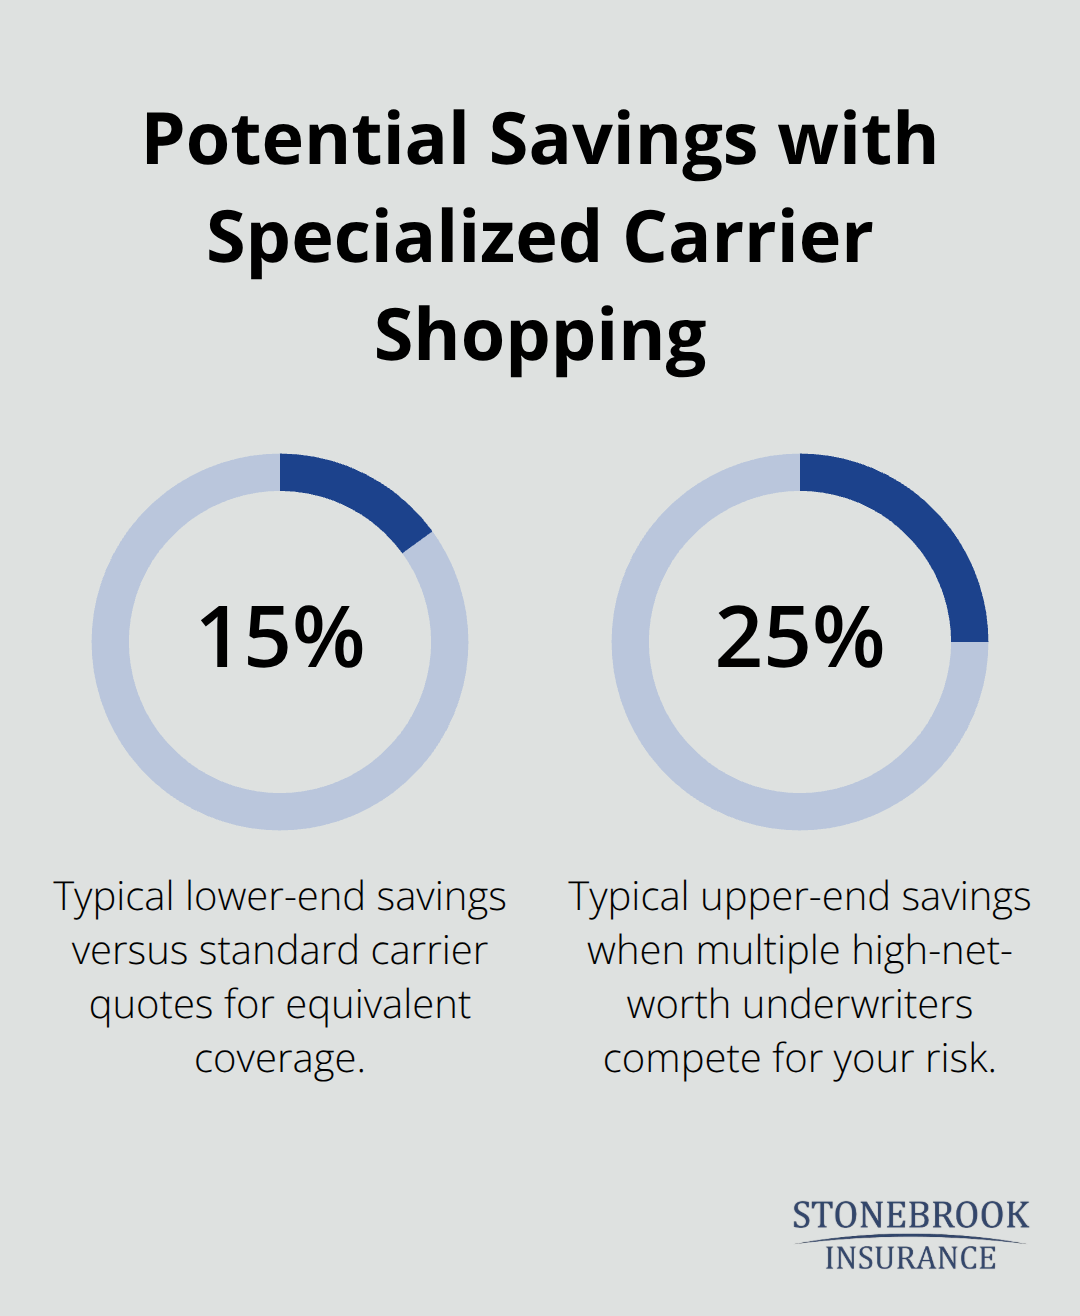
This shopping process typically saves high-net-worth clients 15 to 25 percent compared to standard carrier quotes for equivalent coverage. For a $5 million estate with comprehensive endorsements, this difference translates to $3,000 to $8,000 annually. Beyond pricing, carrier selection determines claim responsiveness and coverage flexibility.
Some carriers impose strict inspection requirements or slow claim processing. Others offer dedicated high-net-worth claims teams and loss-mitigation support that accelerates recovery.
Local Expertise Across Texas
Stonebrook’s three Texas locations in Comanche, McKinney, and Round Rock allow us to serve clients across the state with local expertise and hands-on service. We understand regional risks specific to Texas properties-hail exposure in North Texas, flash flooding in Hill Country, and wildfire proximity in certain areas. When a claim occurs, you work with someone who knows your property, your community, and the local adjusters and contractors managing recovery. This local relationship matters enormously when you need fast, competent claim handling rather than a phone number to a regional claims center.
Final Thoughts
Your luxury home represents far more than a financial asset-it reflects your lifestyle, your taste, and your success. Standard policies and mass-market agents cannot protect what elite properties actually need. High net worth home insurance demands specialists who understand the difference between a $400,000 house and a $5 million estate with custom finishes, art collections, and specialized amenities.
The gap between standard coverage and what your property actually needs grows wider every year. Sublimits on jewelry and art, exclusions for earthquakes and floods, and liability caps designed for average homes leave affluent homeowners exposed to catastrophic financial loss. A single claim on a custom marble staircase or imported Italian tile reveals coverage shortfalls that cost hundreds of thousands of dollars, and these gaps reflect the fundamental mismatch between mass-market underwriting and high-value properties.
We at Stonebrook Insurance approach your protection by starting with your actual property composition, not just its purchase price. We identify which assets fall outside standard limits, which endorsements you genuinely need, and where competitors leave you exposed-then we shop your risk across multiple carriers experienced in elite properties to save you 15 to 25 percent compared to standard quotes. Contact Stonebrook Insurance for a comprehensive risk assessment, and we’ll build a tailored policy that matches your actual wealth and lifestyle.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.