
Your Texas luxury home represents years of investment and personal taste. Standard homeowners policies fall short when it comes to protecting high-end finishes, custom features, and valuable collections that define your property.
At Stonebrook Insurance, we work with affluent homeowners to build luxury property insurance in Texas that matches the true value of what you own. The right coverage makes all the difference when protecting prime real estate.
What Coverage Actually Protects Luxury Homes
Standard homeowners policies cap personal property coverage around $100,000 to $300,000, which leaves most Texas luxury homes severely underinsured. A home with marble countertops, custom millwork, and high-end appliances can easily exceed $2 million in contents alone. High-net-worth property insurance addresses this gap with replacement cost coverage that reflects actual rebuilding expenses rather than depreciated values.
The Replacement Cost Advantage
When a pipe bursts and damages Italian tile flooring or custom cabinetry, actual cash value policies pay only a fraction of replacement costs. Replacement cost coverage eliminates this gap entirely. Actual cash value depreciates your belongings immediately, sometimes by 30 to 50 percent within the first few years. A $50,000 custom kitchen loses significant value under depreciation formulas, leaving you to cover substantial out-of-pocket costs after a loss.
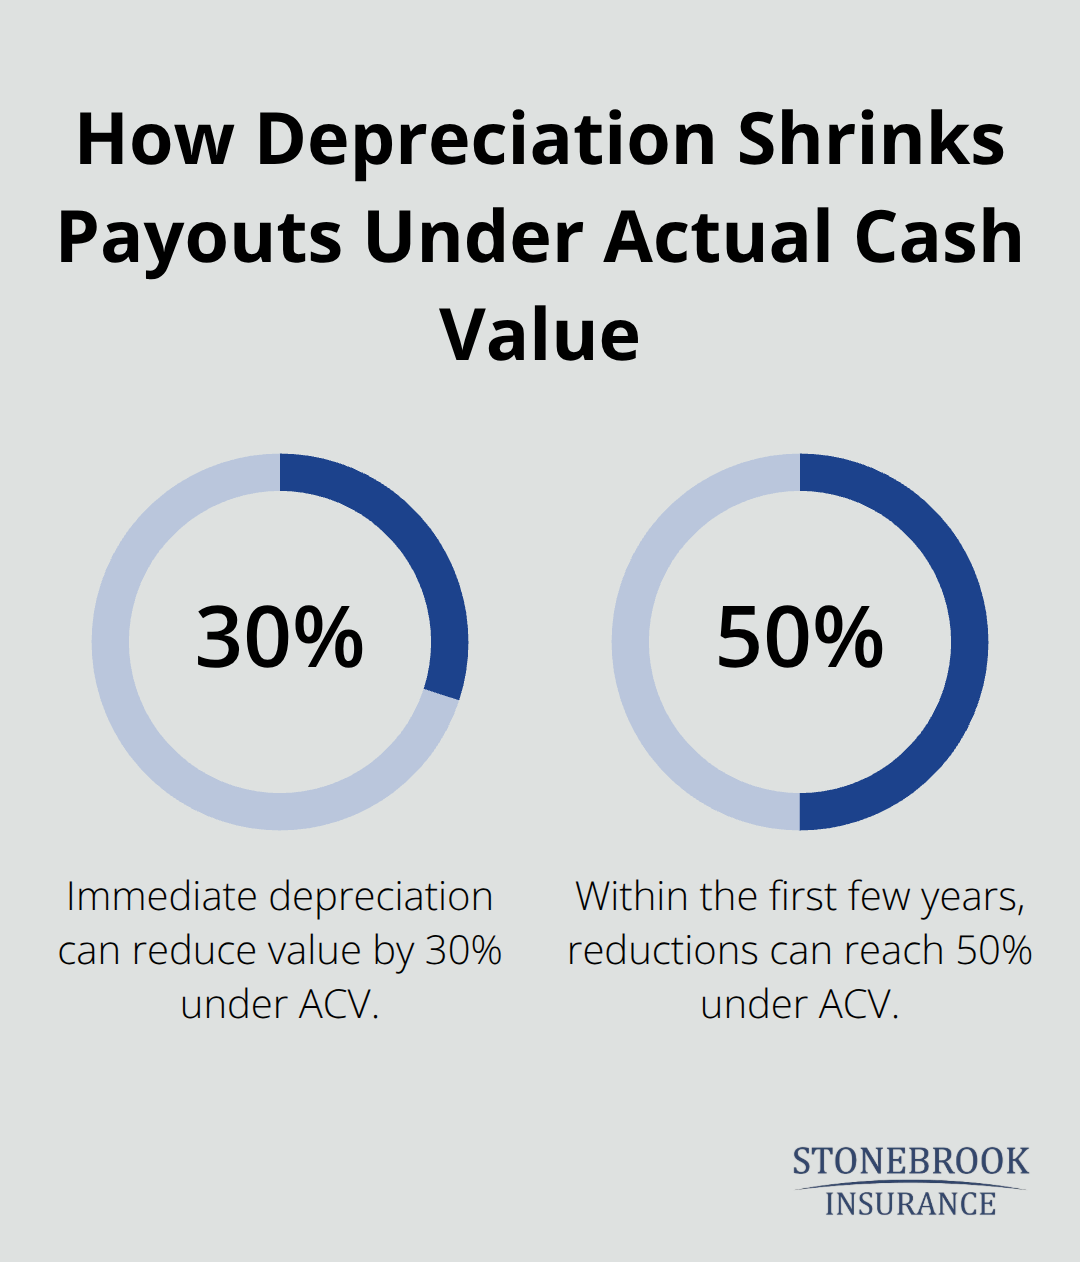
Replacement cost coverage pays what it actually costs to rebuild or replace items with new materials of similar quality. This approach makes sense for luxury homes where custom features cannot be replicated at discount prices.
Liability Protection That Matches Your Wealth
Luxury homes need higher liability limits because affluent properties attract greater exposure. Standard policies typically offer $100,000 to $300,000 in liability protection, but a serious injury on your property could result in a $1 million lawsuit. Try liability limits of at least $1 million for homes valued over $1 million, with umbrella policies extending protection to $2 million or more.
Texas Weather and Specialized Systems
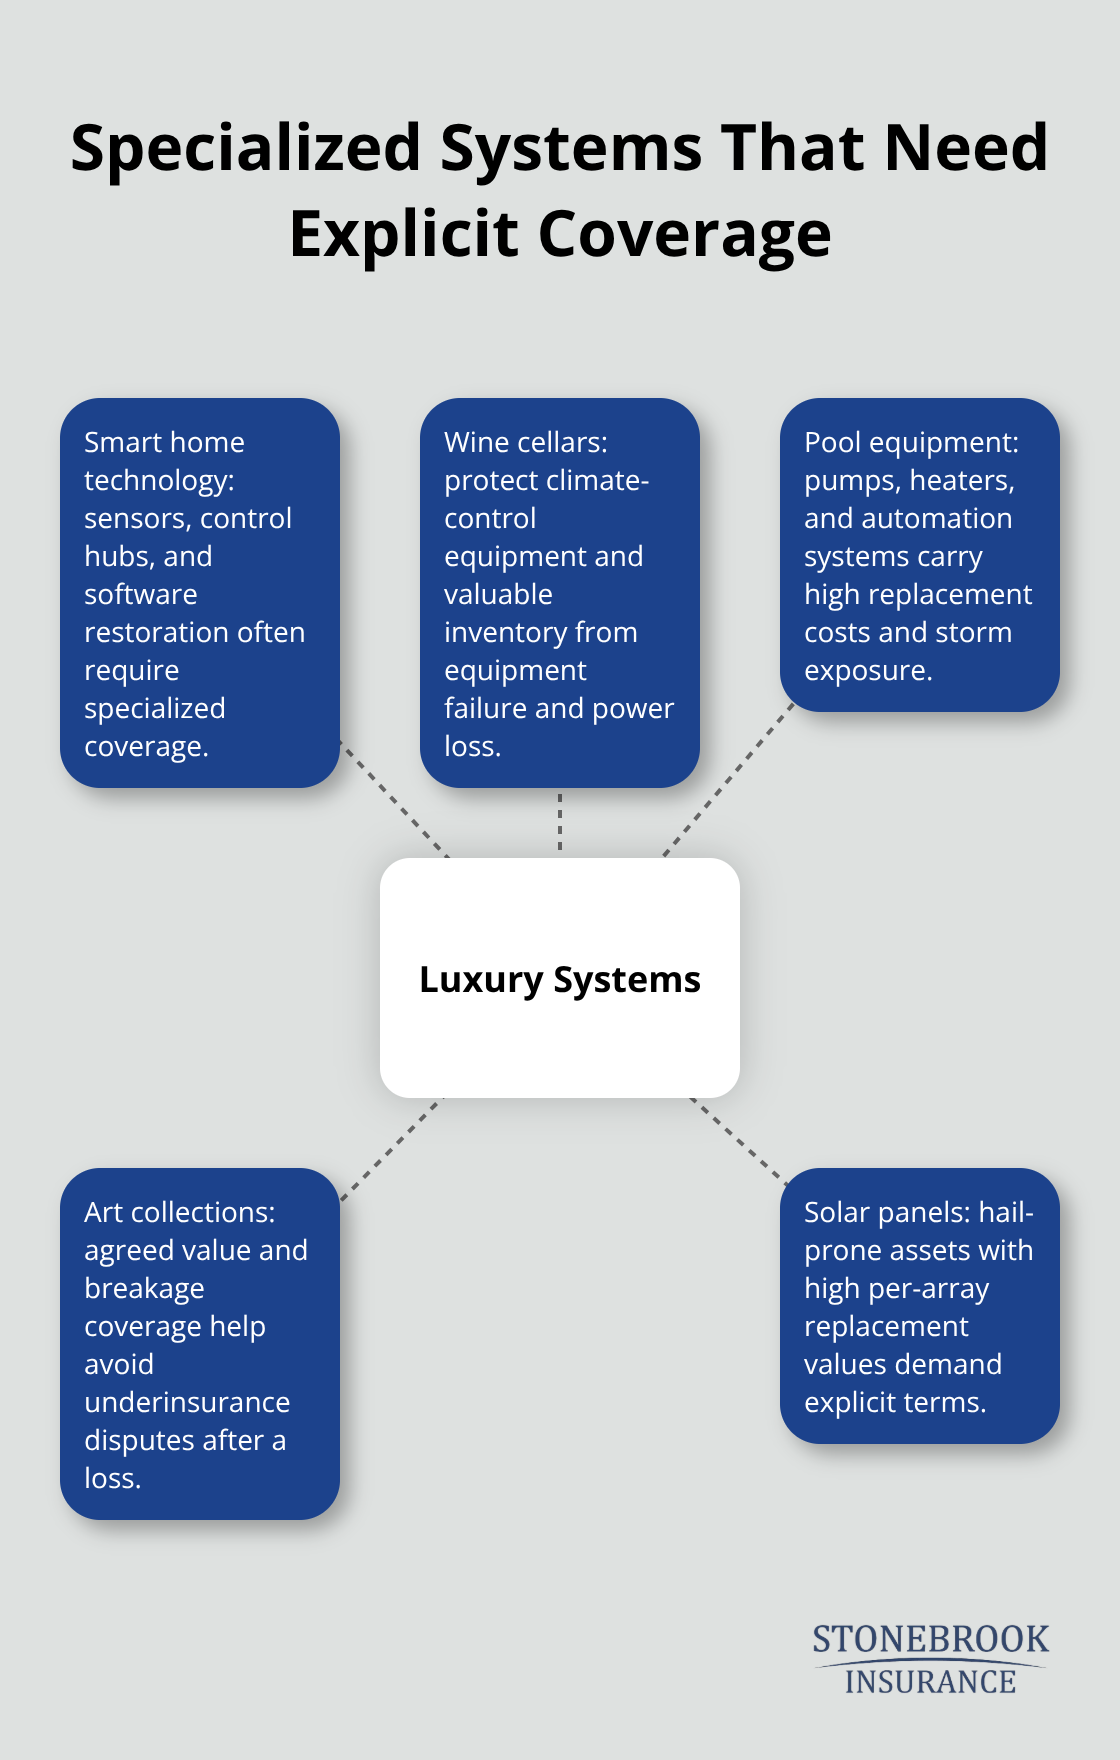
Texas weather compounds these risks significantly. According to the National Oceanic and Atmospheric Administration, Texas experienced 139 hail events in 2023 alone, with some causing over $1 billion in damages statewide. High-net-worth policies include specialized coverage for expensive systems like smart home technology, wine cellars, pool equipment, and art collections that standard policies exclude or severely limit.
Scheduled Endorsements for Fine Art and Collections
Fine art, jewelry, antiques, and collections require individual appraisals and scheduled endorsements rather than blanket coverage limits. Most standard policies cap jewelry coverage at $1,500 to $2,500 per item, which is inadequate for engagement rings or luxury watches. Scheduled personal property endorsements allow you to insure specific items at their appraised values with agreed-upon replacement costs (protecting against underinsurance disputes after a loss). This targeted approach protects what matters most to you. The right coverage strategy requires working with agents who understand high-value properties and can compare options across multiple carriers to find the best fit for your Texas luxury home.
What Makes Texas Luxury Homes High-Risk Properties
Severe Weather Threatens Expensive Systems
Luxury homes in Texas face a specific combination of threats that standard insurance simply doesn’t address adequately. Texas weather creates the most immediate danger-hail alone causes staggering damage across the state. According to the National Oceanic and Atmospheric Administration, Texas experienced 139 hail events in 2023, with cumulative damages exceeding $1 billion statewide. A single hail event destroys expensive roofing materials, damages solar panels worth $15,000 to $25,000, and shatters skylights or custom glass features that cost $5,000 to $10,000 per panel to replace.
Wind damage from severe thunderstorms and occasional tornadoes poses another threat-winds exceeding 100 mph compromise structural integrity and destroy high-end outdoor systems like motorized awnings, retractable glass walls, and premium HVAC equipment. Luxury homes with flat roofs or extensive glass features face elevated exposure compared to standard residential properties.
Criminal Activity Targets Affluent Properties
Beyond weather, affluent properties attract criminal attention at higher rates than average homes. According to FBI Uniform Crime Reports, burglary rates correlate directly with neighborhood wealth levels, and luxury homes with visible high-end features invite theft targeting jewelry, art, wine collections, and electronics. Security systems on expensive properties must go beyond basic monitoring-many high-net-worth homes require professional surveillance integration, smart locks with audit trails, and motion-activated lighting systems that cost $10,000 to $30,000 to install properly.
Specialized Systems Create Hidden Vulnerabilities
The maintenance burden on luxury systems creates another hidden risk that most homeowners underestimate. High-end HVAC systems with zoned climate control cost $15,000 to $40,000 to replace, smart home automation networks require specialized technicians at $150 to $300 per hour, and pool systems with salt-water generators and automated cleaning equipment can exceed $50,000 in total value. When these systems fail or sustain damage, repair costs spike dramatically because replacement parts must match original specifications and installation requires certified technicians.
Wine cellars with precise temperature and humidity controls represent a specialized risk-a single malfunction destroys collections worth $50,000 to $500,000, yet standard homeowners insurance provides minimal coverage for this exposure. Custom landscaping with mature trees, irrigation systems, and outdoor kitchens adds another layer of vulnerability to storm damage and requires specialized assessment during the insurance quote process.
Coverage Gaps Leave You Exposed
These specific system vulnerabilities demand more than generic policy limits. Standard homeowners policies simply cannot account for the replacement costs associated with luxury home features and high-value systems. The right insurance strategy identifies these exposures and structures coverage that addresses real replacement costs rather than inadequate blanket limits. Understanding what your luxury home actually contains-and what it costs to replace-becomes the foundation for adequate protection.
How to Get an Accurate Luxury Home Insurance Quote
Start with a Detailed Property Inventory
Finding the right luxury home insurance quote requires more than calling a single agent and accepting the first number you receive. Most standard insurance agents lack experience pricing high-value properties, which means their quotes systematically underestimate replacement costs and miss critical coverage gaps. The quote process should start with a detailed property inventory that accounts for every high-end system, material upgrade, and valuable item in your home.
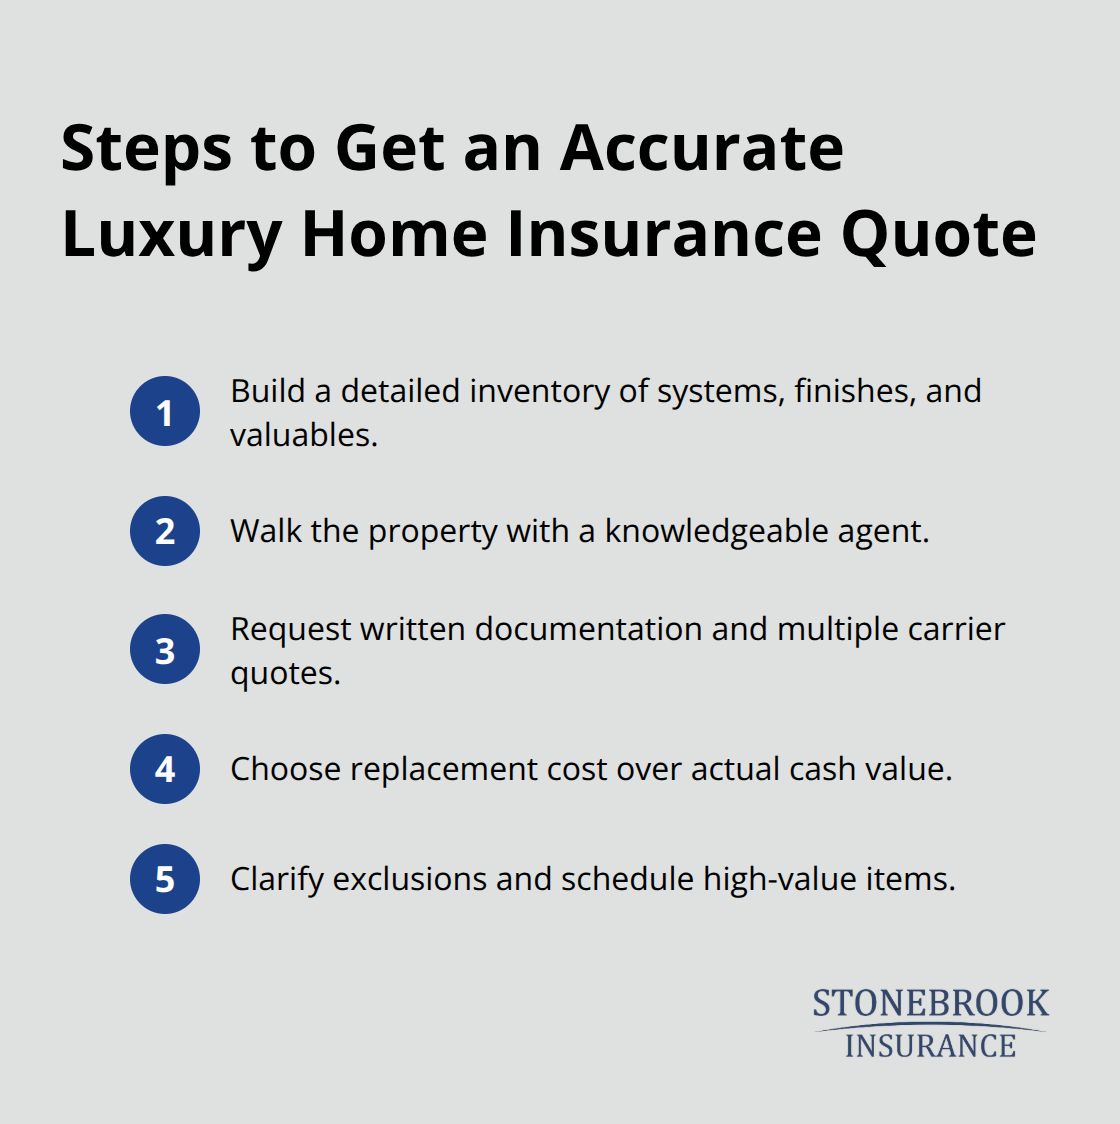
Walk through your property with an agent who asks specific questions about your HVAC system specifications, solar panel costs, wine cellar equipment, smart home integration, and any custom features that deviate from standard construction. A thorough inventory typically reveals $500,000 to $1.5 million in additional value that generic replacement cost estimates miss entirely.
Request Written Documentation and Multiple Quotes
Ask your agent to provide written documentation of what they’re quoting and why-replacement costs should reference actual contractor bids for specialized work rather than generic square-footage calculations. Most importantly, request quotes from multiple carriers simultaneously. Insurance pricing for luxury homes varies dramatically across companies because underwriters assess risk differently.
One carrier might charge $4,500 annually while another charges $7,200 for identical coverage on the same property, according to data from the National Association of Insurance Commissioners showing premium variation of 40 to 60 percent across carriers for high-value properties. This variation means shopping multiple companies isn’t optional-it’s the only way to avoid overpaying significantly.
Choose Replacement Cost Over Actual Cash Value
Replacement cost coverage versus actual cash value represents the most consequential decision in your quote. Actual cash value sounds cheaper because it produces lower premiums. However, actual cash value depreciates everything immediately, meaning a $40,000 custom kitchen island loses 30 to 50 percent of its value instantly when damaged, leaving you to cover the gap out of pocket.
Replacement cost coverage eliminates this problem by paying what it actually costs to rebuild with materials of similar quality and craftsmanship. For luxury homes where custom features cannot be sourced at bargain prices, replacement cost is non-negotiable.
Clarify Coverage for Specialized Systems and Collections
When requesting quotes, specify replacement cost as your requirement and ask carriers to explain any exclusions or limitations in writing. Some carriers exclude coverage for certain system types or cap reimbursement on specialized equipment, which creates hidden gaps in protection. Demand clarity on whether your wine cellar, pool equipment, smart home systems, and outdoor kitchens are covered under the base policy or require separate endorsements.
Scheduled endorsements for fine art, jewelry, and collections should list each item individually with its appraised value rather than applying blanket limits. This approach prevents disputes after a loss because the carrier has already agreed to specific replacement values in advance. The quote process takes time when done properly, but rushing this decision costs far more than the hours invested in getting it right.
Final Thoughts
Protecting a Texas luxury home requires more than standard insurance and generic quotes. Your property demands coverage that reflects its actual replacement costs, specialized systems, and high-value collections. The difference between adequate protection and severe financial exposure often comes down to working with agents who understand high-net-worth properties and take time to assess what you truly own.
Standard policies leave gaps that become painfully obvious after a loss. When hail damages your solar panels or a pipe bursts behind custom millwork, you’ll wish you’d invested in replacement cost coverage and scheduled endorsements for your most valuable items. The agents you work with should ask detailed questions about your HVAC specifications, wine cellar equipment, smart home systems, and any custom features that deviate from standard construction.
Contact Stonebrook Insurance to discuss your luxury property insurance Texas needs. Bring your property inventory, recent contractor bids for any upgrades, and appraisals for high-value collections. A thorough conversation with our team takes a few hours but prevents years of regret if something goes wrong.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.